Within a day or two of arriving in Peru, you will hear the question. At the menú lunch spot, at the fruit stall, in the back of a taxi: "¿Tienes Yape?" It is asked so casually that saying no feels like admitting you forgot your shoes. This article answers the questions expats and long-stay visitors actually type into search bars after that moment, starting with the obvious one.
What are Yape and Plin, exactly?
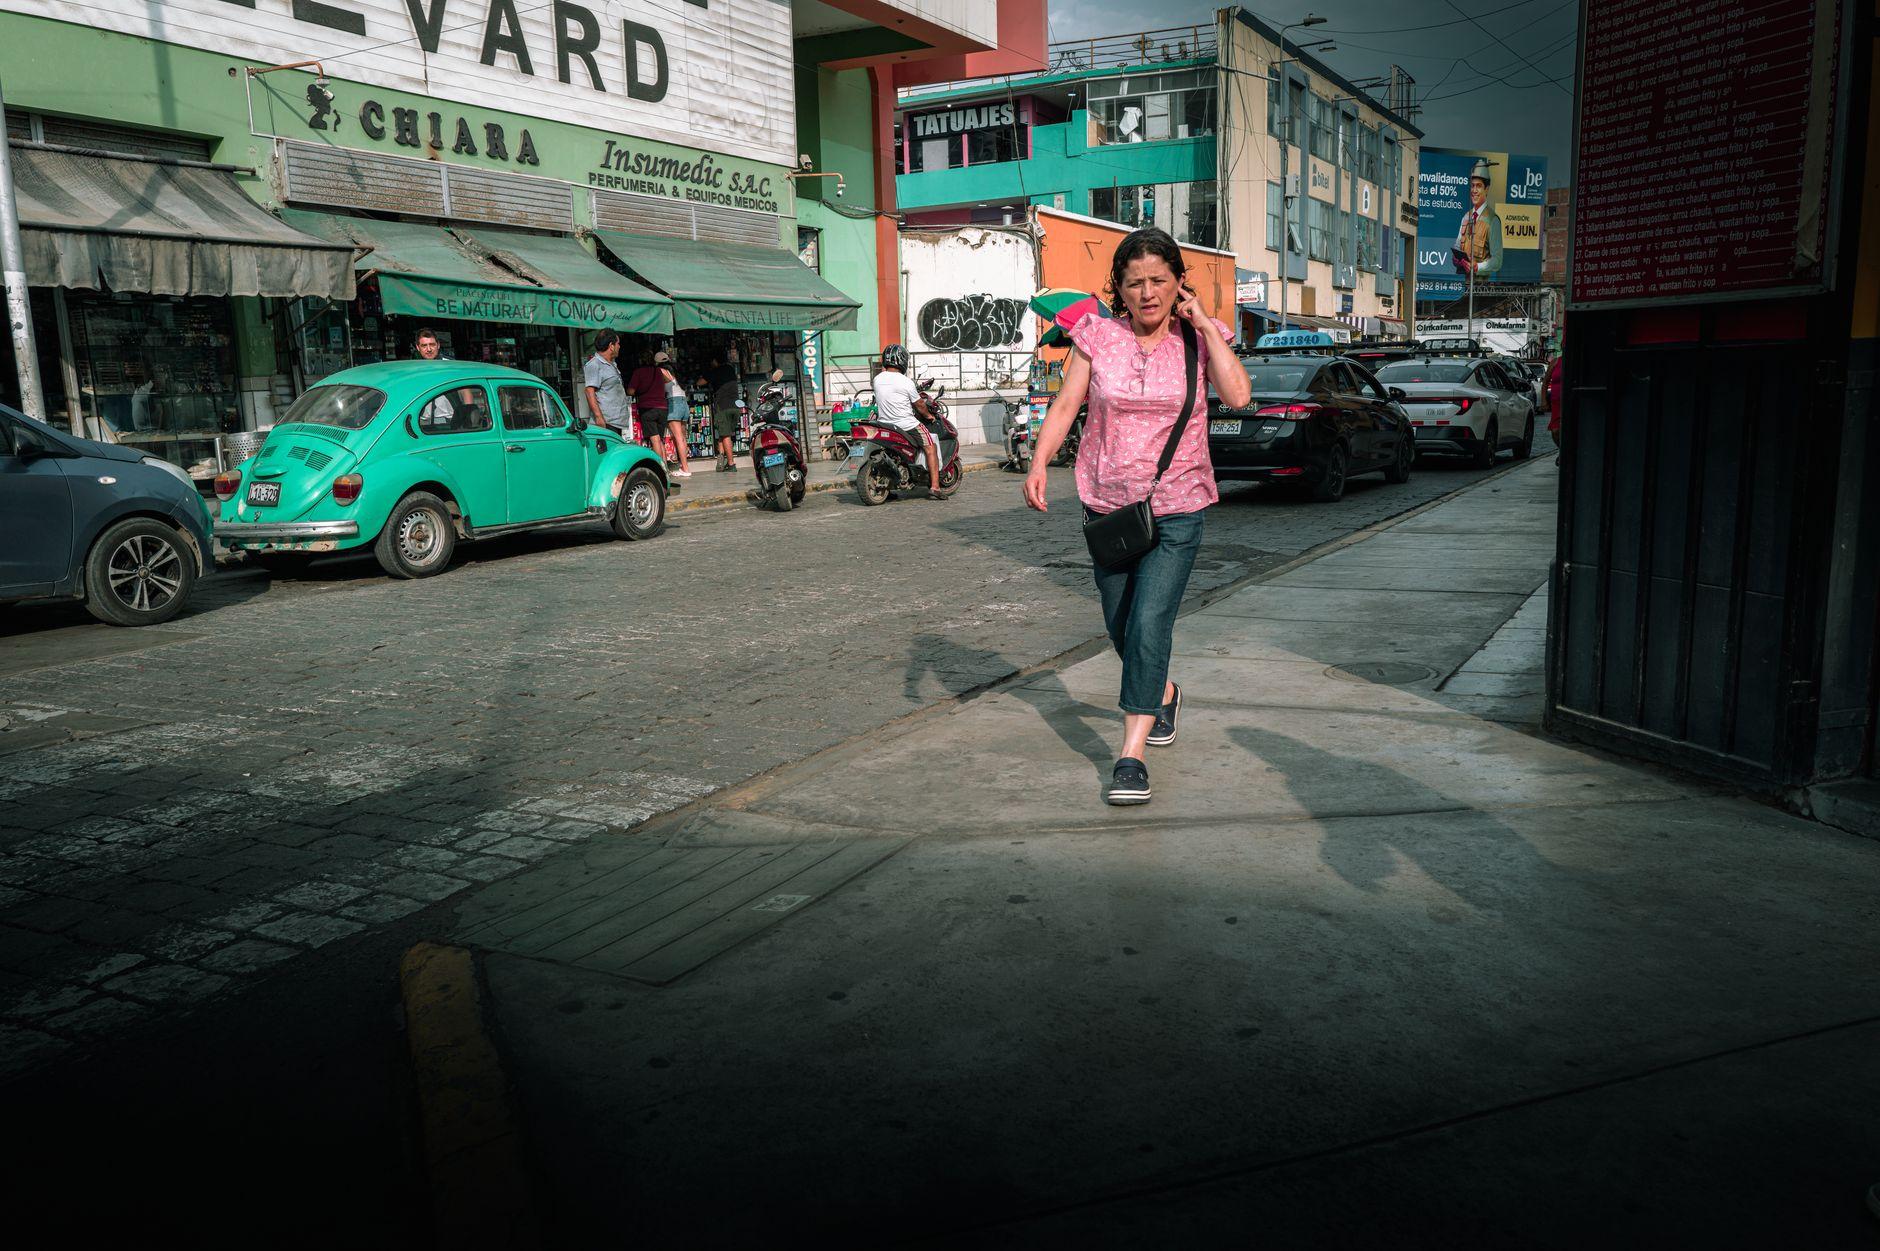
They are Peru's two dominant QR wallet apps. Yape (the purple one, run through BCP) and Plin (backed by a group of other Peruvian banks) let locals pay each other and pay merchants instantly by scanning a QR code or entering a phone number. They have spread far beyond Lima's cafes. Market vendors in Arequipa, mototaxi drivers in Iquitos, the woman selling emoliente from a cart at 7 a.m., all of them have a QR code taped up or saved as their phone's lock screen. For many small merchants, Yape or Plin is not an alternative to a card machine. It replaced the card machine before one ever arrived.
Can a foreigner just download Yape or Plin and sign up?
This is where most new arrivals hit a wall. Both apps are built around Peruvian identity documents and Peruvian bank accounts. If you are on a tourist stamp or a short-term stay, you almost certainly do not have either, and getting a local bank account as a non-resident ranges from slow to practically impossible depending on the branch and your paperwork. Expats with residency and a carné de extranjería eventually get set up, but that process takes months. If you are in Peru for weeks or a season, the honest answer is: no, the local apps are not realistically available to you.
So is it just cash, then?
Cash works everywhere, but Peru's cash scene comes with a specific headache that guidebooks warn about for good reason: counterfeit bills. Fake soles circulate widely enough that locals routinely hold notes up to the light, feel the paper, and check the security thread, and merchants will do the same to yours. Tourists are a known target for getting fakes passed back as change, especially in taxis and at night. You can learn to check bills (and you should), but it adds friction to every single purchase, and if you do end up with a fake fifty, nobody will take it off your hands. This is a big part of why Peruvians themselves moved to Yape so fast. Not carrying cash means not worrying about what is in your wallet being real.
Can I pay with my foreign credit card instead?
In a mall, a chain supermarket like Plaza Vea or Tottus, or a tourist-facing restaurant in Miraflores or Cusco's centro, yes, usually. Step outside that bubble and the picture changes fast. The menú place charging a few soles for lunch, the market stall, the colectivo, the corner bodega, these are QR and cash territory. Cards also bring their own costs: foreign transaction fees from your home bank and the occasional dynamic currency conversion trap at terminals that offer to charge you in dollars or euros at a rate that favors nobody but the machine. A card is worth carrying in Peru. It is not a plan for daily life.
How do I actually pay at the places that only take Yape?
This is the gap Moreta Pay was built for. It lets you scan the same QR codes locals scan, the ones already sitting on the counter, without needing a Peruvian bank account or a Peruvian ID. You load the wallet from home (US bank via Plaid or ACH, European SEPA, UK Faster Payments, Canadian e-Transfer, or an international card) in your own currency. At the stall, you scan the merchant's code, see the amount, the exchange rate, and the merchant's name on screen, and confirm. The conversion to soles happens inside the wallet and the vendor is paid instantly, the same as if a local had paid. No new signup hoops in-country, no handing over bills and squinting at the change you get back.
What about everyday situations like taxis and markets?
A few real scenarios where QR saves you in Peru:
- Taxis and mototaxis. Many drivers prefer QR because they do not want to carry change either. Agreeing a fare and scanning at the end avoids the "no tengo sencillo" shuffle entirely.
- Mercados. At a produce market, you might buy from four different vendors in ten minutes. Scanning each stall's code beats breaking a hundred-sol note four times.
- The menú lunch. Set-price lunches are the backbone of expat eating in Peru, and they are exactly the kind of small, family-run business that went straight to Yape.
- Splitting with local friends. When someone covers the table and everyone else yapes them, you can pay the restaurant's QR directly for your share instead of being the one person digging for coins.
Does any of this work for online purchases and bills?
Yes, where the checkout offers a QR payment option. Moreta Pay handles QR-based online payments on platforms like Trip.com and Agoda, which covers a lot of in-country bus, hotel, and flight booking, and it can pay bills in supported countries. For an expat settling into an apartment in Lima or Cusco, being able to clear a utility or service bill by QR, without a local account, removes one of the more annoying errands of unbanked life abroad.
Should I carry any cash at all in Peru?
Yes, some. Remote areas, tiny purchases in villages, propinas, and the occasional vendor whose phone has died all still call for soles. The sensible setup for 2026 is a modest amount of small-denomination cash (small notes are both harder to counterfeit profitably and easier to spend) plus a QR wallet for everything else. That keeps your ATM runs rare and your exposure to fake bills low. If your travels continue south, the balance shifts again, as we covered in our look at how payments split between QR cities and cash country in Bolivia.
One counter, two stickers: which QR do I scan?
You will often see both a Yape code and a Plin code taped side by side, sometimes with a bank's own code as a third. Peru is one of the countries where interoperability arrived in layers rather than all at once, a pattern we explored in why some counters print three QR codes and others just one. The practical advice: scan, then check the merchant name and amount on your screen before confirming. If something looks off, ask the vendor which code is theirs. They deal with this daily and will point.
What would a typical day without cash look like?
Morning jugo at the market, scanned. Combi fare, okay, that one is coins. Menú lunch, scanned. An afternoon at a cafe in Barranco, scanned or card. Groceries at the bodega, scanned. Dinner out, scanned, and your share of the group bill paid straight to the restaurant's code instead of the awkward cash reshuffle. The point is not purity, it is that cash becomes the exception you keep for edge cases rather than the stack you guard all day.
Peru's payment culture is further along than most visitors expect, and the frustrating part was never the technology, it was the door being closed to anyone without a local bank. Open that door with Moreta Pay before your flight lands, and the next time someone asks "¿Tienes Yape?" you can just hold up your phone and scan.