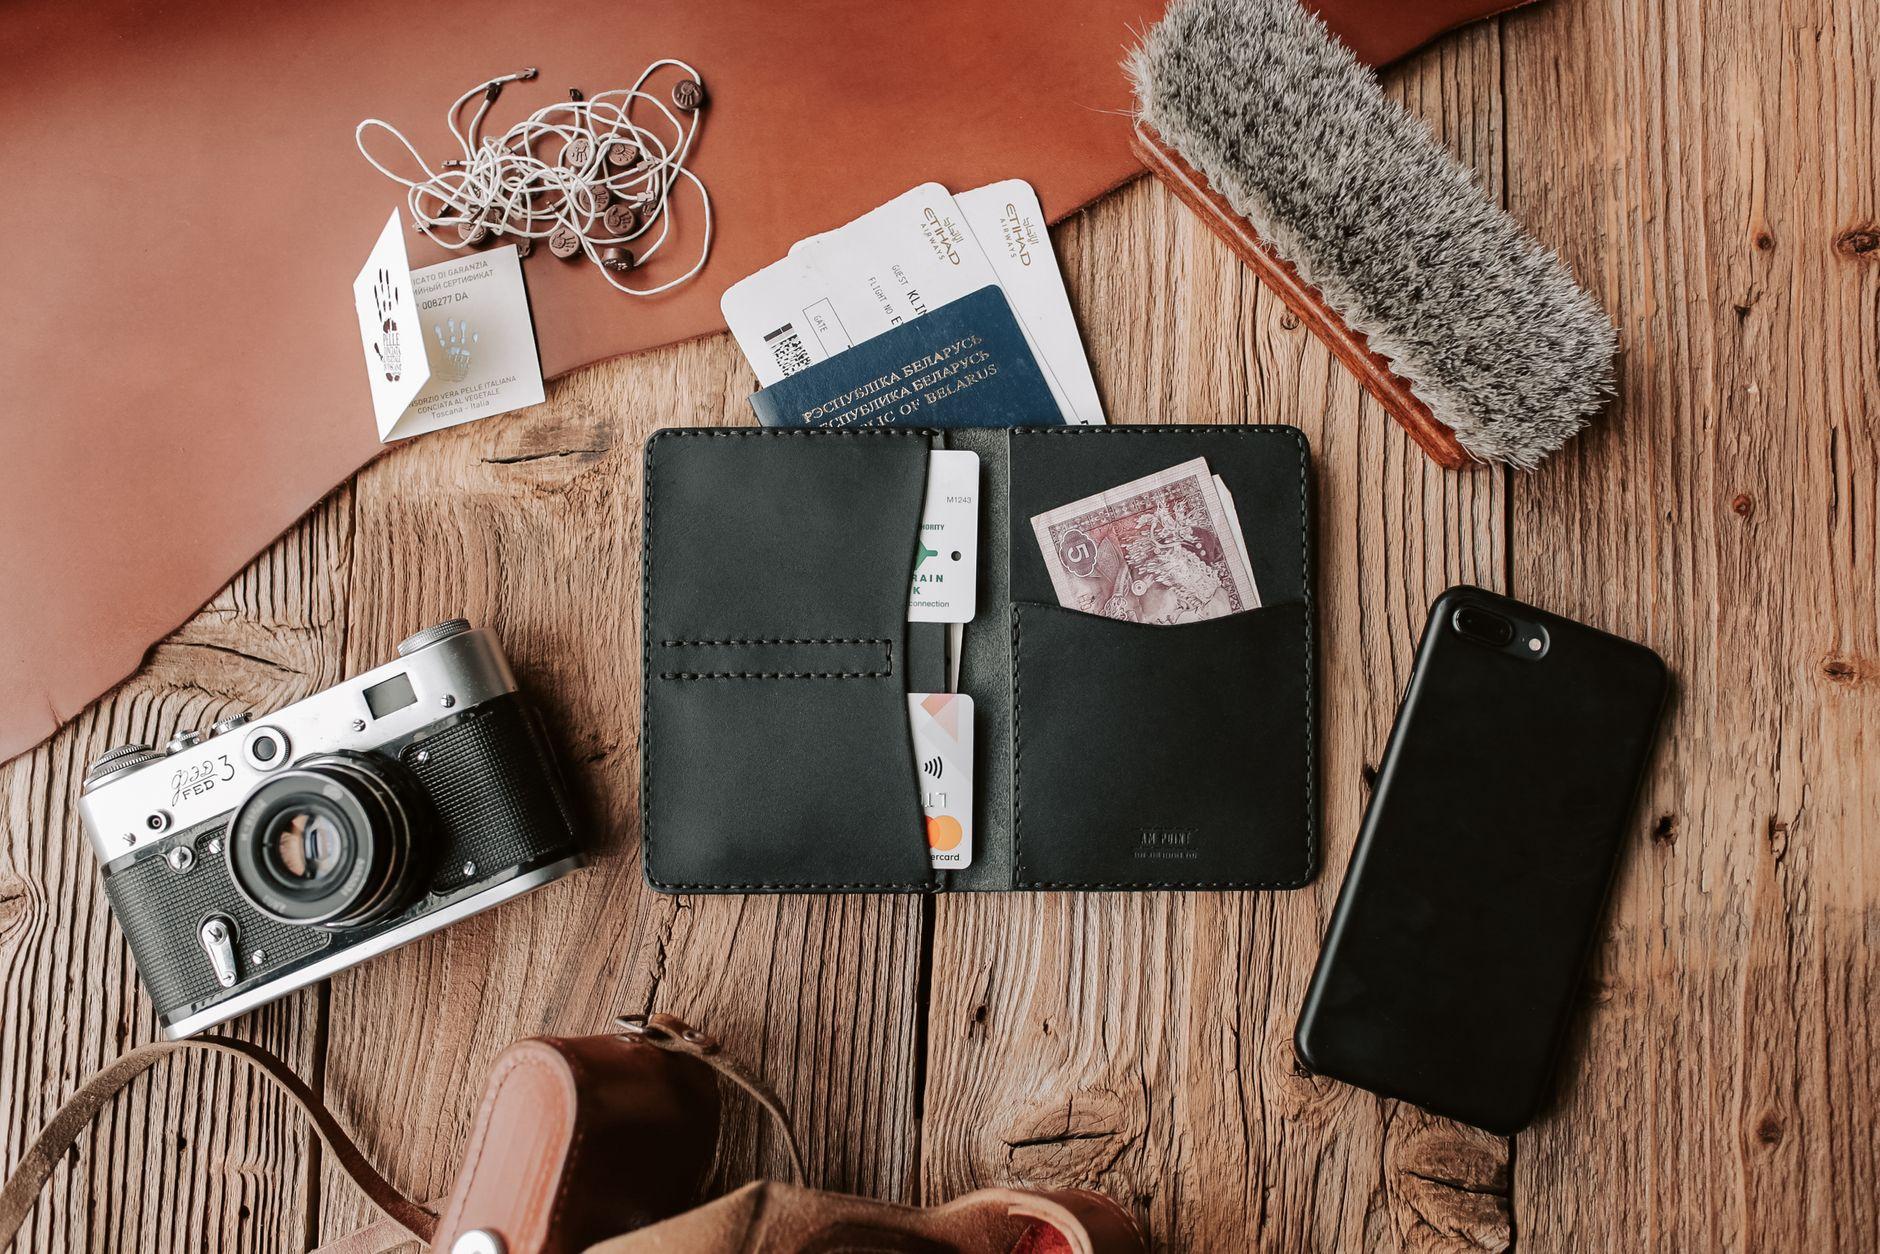
A phone dies at a KL Sentral platform, a screen cracks against a tuk-tuk door frame near Phsar Thmei, a login gets locked after three failed password attempts at a Copacabana ATM. Any one of these can turn a fully-funded trip into a standstill. If every dollar you brought sits in a single app on that single phone, the failure mode is not an inconvenience, it is a full stop on your ability to pay for anything until you fix the problem, often in a country where you do not speak the language and the local bank branch closes at 3pm.
Travel money safety is not really about which app has the best exchange rate. It is about what happens on the day something goes wrong with the tool you were relying on. Moreta, a FinCEN-registered Money Services Business built for travelers making local QR payments across Malaysia's DuitNow network, Cambodia's KHQR system, and Brazil's Pix rails, treats redundancy as a design question, not an afterthought. Below is a practical plan for splitting your travel funds across tools so that no single point of failure can strand you.
What does "redundancy" actually mean for travel money?
Redundancy means having at least two independent ways to pay that do not share a single point of failure. If your phone breaks, your backup should not also be on that phone. If your primary card gets frozen for suspected fraud, your backup should not be issued by the same bank using the same fraud-detection system.
A useful analogy: airlines do not put both engines on the same fuel line. If one engine loses fuel pressure, the aircraft does not lose all thrust, because the two systems are physically separated. Your travel money should work the same way. A phone-based wallet, a physical debit card, and a modest cash reserve each fail for different reasons (dead battery, magnetic strip damage, pickpocketing), so combining them means one failure does not cascade into the others.
Fraud exposure varies by region, and regions with higher fraud rates are also where card issuers tend to be more trigger-happy about freezing accounts for "suspicious activity," which is exactly the moment your backup plan needs to already exist.
How should you split your money before a Malaysia trip?
Malaysia runs on DuitNow QR, a national standard that lets any participating bank app or e-wallet scan the same code at a mamak stall in Bangsar or a pasar malam stall in Petaling Jaya. DuitNow, like Pix and KHQR, is built on the EMV QR standard, using tokenization and real-time bank validation so the merchant gets paid instantly regardless of which app the customer used.
A workable three-way split for Malaysia:
- Primary: a QR wallet like Moreta, topped up from your home bank or card, for day-to-day spending at hawker stalls, convenience stores, and most retail.
- Backup: a physical debit or credit card from a different issuer than your primary card, kept separate from your phone, for hotel deposits and larger purchases.
- Cash reserve: RM50 to RM100, sized for toll booths on older highway stretches, some wet market stalls, and parking attendants who still deal only in coins and small notes.
Notify your home bank of your travel dates before you leave [bankwithunited.com]. A card that gets silently declined at a Grab Pay merchant because the issuer flagged an unusual country is a redundancy plan failing at the worst moment.
What's different about a redundancy plan for Cambodia?
Cambodia complicates a straight cash-versus-card plan because the country runs on two currencies simultaneously. Riel and US dollars circulate side by side, and KHQR, Cambodia's national QR standard, settles in whichever currency the merchant has registered, which is not always obvious from the code itself.
This is why a Cambodia-specific reserve looks different from Malaysia's:
- Primary: a QR wallet funded ahead of time, since Cambodia's ATM network outside Phnom Penh and Siem Reap can be sparse and often charges a flat withdrawal fee regardless of amount.
- Backup: small denominations of both USD and riel, because a moto-taxi driver or a stall at Phsar Chas may only deal in one or the other, and getting exact change in a market that mixes both currencies is its own small negotiation.
- A written note of your hotel's address in Khmer script, not strictly a payment tool, but part of the same redundancy logic: if your phone dies and you cannot pull up a map or translation app, you still need a way to get back.
The honest caveat here is that rural areas and temple donation boxes near Angkor still run entirely on small cash. No app closes that gap completely, so budget a genuinely separate reserve of small notes for exactly those moments rather than assuming your QR wallet covers everything.
How does Pix change the redundancy math in Brazil?
Pix is Brazil's instant payment system, run by the Central Bank, and it has become the default way Brazilians pay for nearly everything from a padaria coffee to a taxi fare, using a QR code, phone number, or CPF as the payment key. Pix brazil payments settle in seconds between bank accounts, which is faster than a card authorization and does not depend on the merchant having a card terminal at all.
The redundancy risk in Brazil is less about currency confusion and more about network dependency. Pix requires a live data connection on both sides of the transaction. If you are in an area with weak signal, a stall in a smaller town outside São Paulo or a beach kiosk in Bahia, having a card as backup matters more here than in a market where cash is the norm.
- Primary: a QR wallet supporting Pix, for the overwhelming majority of transactions where you have signal.
- Backup: a card with no foreign transaction fee, because Brazil's card networks are dense in tourist areas even where Pix penetration briefly gaps out.
- Cash reserve: R$50 to R$100, mainly for street vendors and public restrooms that still expect coins.
Is it safer to rely on a multi-currency app like Wise or Revolut instead?
Multi-currency apps solve a different problem than local QR access. Neither Wise nor Revolut connects natively to DuitNow, KHQR, or Pix merchant codes, which means you are typically still swiping a card rather than scanning the same QR the vendor next to you is using. Either app is a reasonable piece of a redundancy plan, but neither replaces the value of a wallet built to scan local QR codes at the point of sale.
Frequently Asked Questions
How much cash should I actually carry as a backup in Malaysia, Cambodia, or Brazil?
Size it to specific gaps, not a percentage rule. RM50-100 in Malaysia for tolls and parking, small USD and riel notes in Cambodia for rural stalls and temple donations, R$50-100 in Brazil for vendors without Pix or card terminals. Do not carry large sums.
Should I tell my bank before traveling to these countries?
Yes. Giving your bank a heads-up before you travel is a standard step to prevent your card from being frozen for suspected fraud the moment you use it abroad [bankwithunited.com].
Is it risky to keep all my travel funds in a phone-based wallet?
Yes, if it is your only method. A dead battery, theft, or a locked account removes your entire spending ability at once. Split funds across at least one app, one physical card, and a small cash reserve.
Should I keep my cash and cards in the same place?
No. Spreading cash and cards across a wallet, a money belt, and a hotel safe means a single theft does not wipe out your entire trip budget [anpost.com].
What is dynamic currency conversion and why does it matter here?
DCC is when a card terminal or ATM offers to charge you in your home currency instead of the local one. Always decline it and choose the local currency; the terminal's conversion rate is worse than what your card issuer or wallet will apply.
Does a QR wallet like Moreta replace the need for a backup card?
No. Even the best single tool should not be your only tool. Moreta is designed as a strong primary method for local QR payments, but the redundancy principle in this article applies to Moreta the same way it applies to any other app.
About Moreta
Moreta is a Delaware-incorporated, FinCEN-registered Money Services Business, backed by Y Combinator. The app lets you convert your home currency at the point of payment and shows the merchant name, amount, and exact rate before you confirm, so there is no guessing at the register. Funds are held in protected accounts via Plaid-connected banking infrastructure.
If you are planning a trip through Malaysia, Cambodia, or Brazil and want a primary payment method built around each country's actual QR rail, visit Moreta to see how it fits into your own redundancy plan.
References
- 8 Things You Can Do to Keep Your Money Secure During Travel (bankwithunited.com)
- Radware Captcha Page (anpost.com)