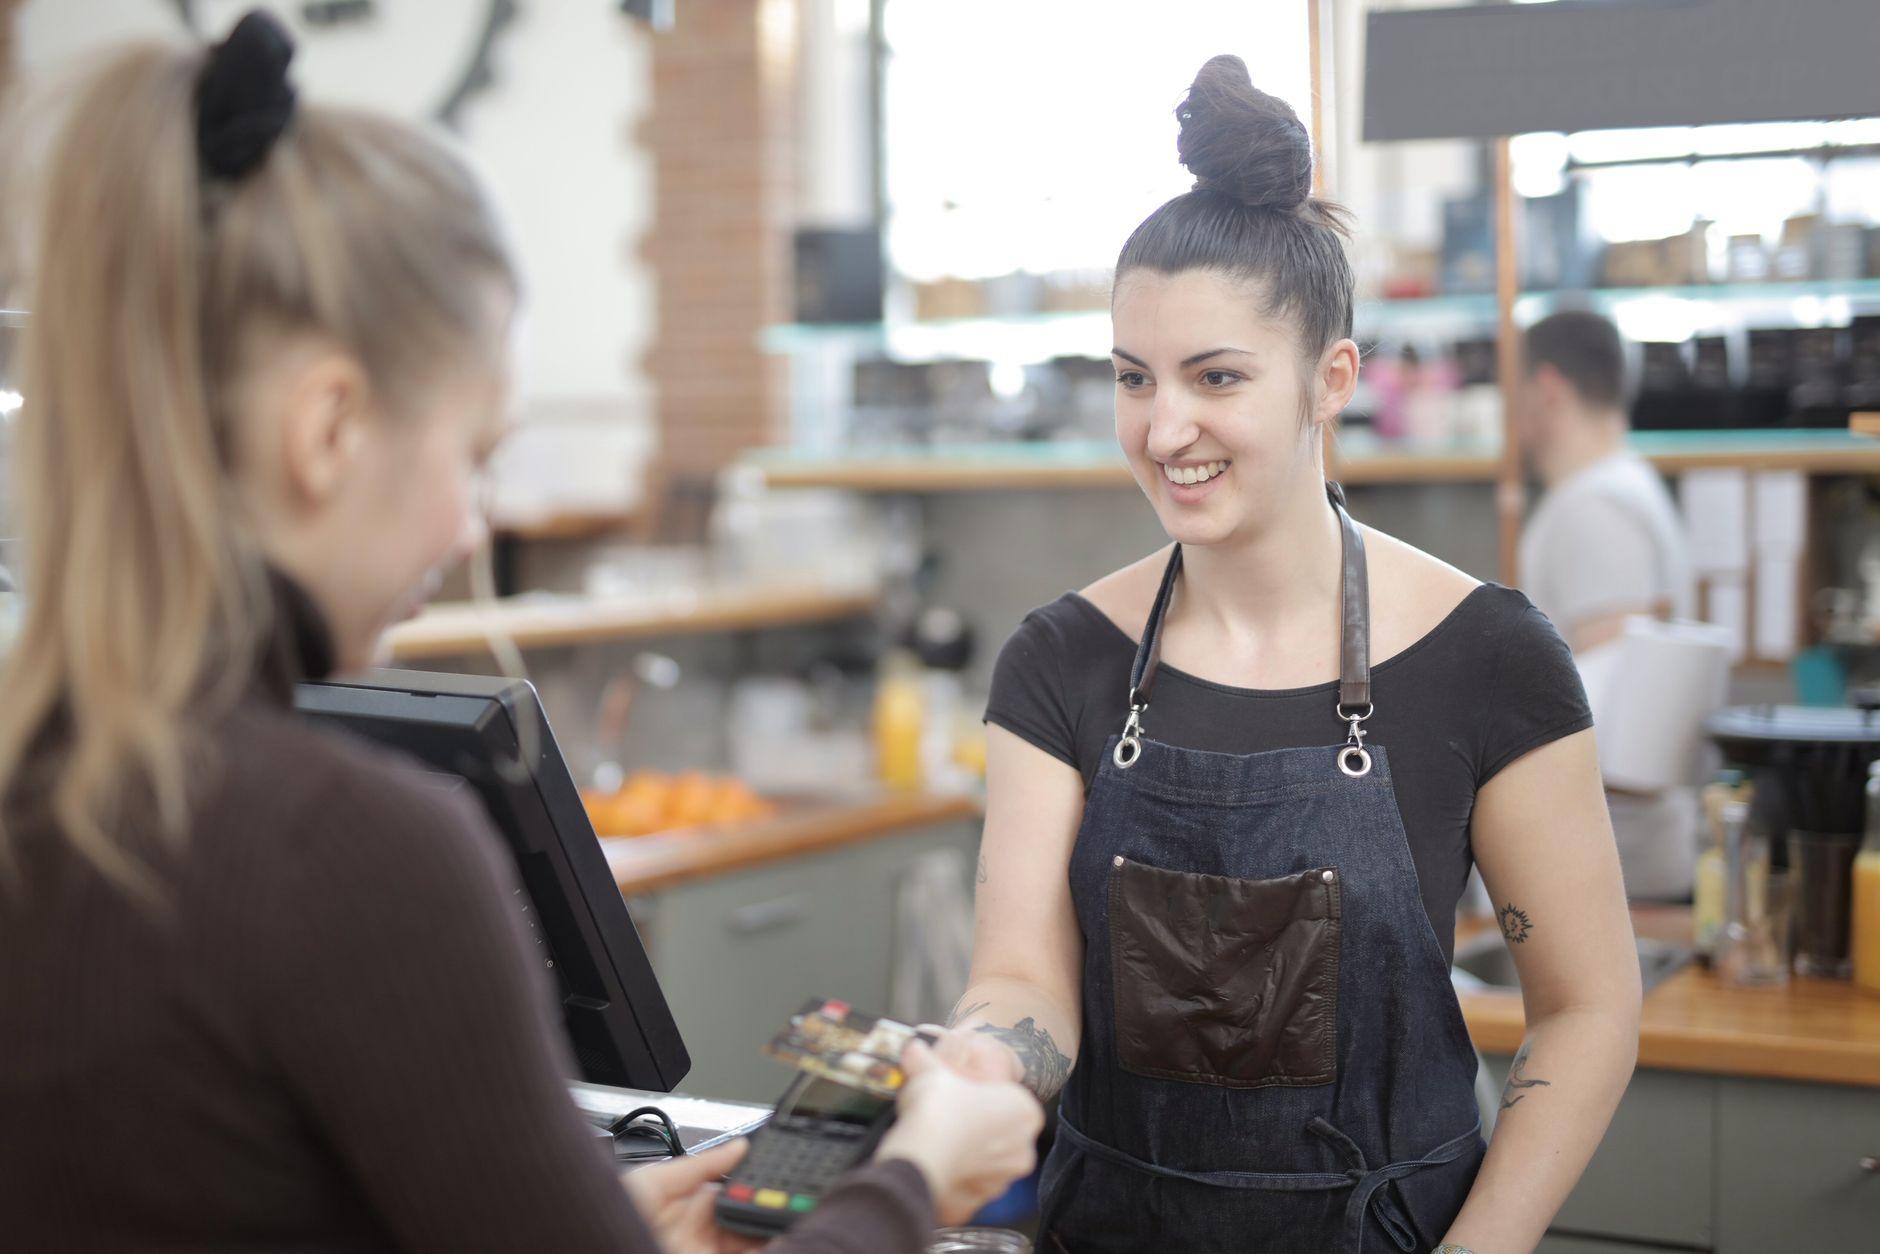
You're at a mamak counter in Kuala Lumpur, plate of nasi lemak in front of you, 12 ringgit. Coffee, 3 more. You tap your credit card and the transaction goes through in seconds. Two weeks later, back home, you scan your statement and the total doesn't quite add up. There's an extra line, small, easy to miss, sitting right under the original charge. That's the foreign transaction fee, and on most basic credit cards it runs close to 3 percent of every purchase you make abroad.
This fee is not a scam and it's not hidden in the sense of being illegal. It's disclosed, itemized, and legally mandated to be so. But "disclosed" and "visible when you actually need it" are two different things, and that gap costs travelers real money on every swipe.
What exactly is a foreign transaction fee?
A foreign transaction fee is a percentage-based charge that your card issuer adds to any purchase processed in a foreign currency or routed through a foreign bank, even if you're charged in US dollars. The standard rate at most major issuers is around 3 percent, and that number is not arbitrary. It's typically composed of two separate charges stacked together: a network fee of about 1 percent charged by Visa or Mastercard for processing the cross-border transaction, and an additional markup of roughly 2 percent charged by your issuing bank on top of that.
Think of it like a toll road with two toll booths. The card network (Visa, Mastercard) collects a small toll for routing your transaction internationally. Then your bank, sitting downstream, adds its own toll before the charge ever reaches your statement. You only see the combined total, which is why it reads as one flat "foreign transaction fee" instead of two separate charges.
Where does the fee actually appear on your statement?
The fee is assessed mathematically after your purchase amount has already been converted into your home currency, then itemized as its own line directly below the original transaction. So if you spend 100 ringgit on dinner in Kuala Lumpur, your statement won't show one blended number. It shows the converted dollar amount for the meal, and then, right underneath it, a second smaller charge labeled something like "foreign transaction fee" or "international transaction fee."
Here's the problem: most people scroll past that second line because it's small in isolation. A 3 percent fee on a $25 meal is 75 cents. It doesn't feel worth investigating. But multiply that across every meal, every cab ride, every souvenir over a two-week trip, and the credit card fees abroad add up to a real percentage of your total spending, quietly, one line at a time.
Why do some cards charge it and others don't?
This is where the fee stops being universal and starts being a product decision. Standard no-frills credit cards typically still charge the full 3 percent on international purchases, because the issuer assumes most cardholders use these cards domestically and international transactions are the exception, not the design target. Premium and travel-specific cards, on the other hand, usually waive the fee entirely as a core cardholder benefit, precisely because the issuer expects and wants you to use that card overseas.
Chase, Capital One, and American Express all follow this pattern: their basic cards charge the standard fee, while their travel and premium tiers waive it. The fee is not fixed by law or by network. It's a business decision by your specific issuer, tied to which product tier you're holding.
| Card type | Typical foreign transaction fee | Why |
|---|---|---|
| Basic card | ~3% | Issuer doesn't prioritize international use |
| Premium travel card | 0% | Issuer competes on travel benefits |
| Airline/hotel co-brand card | Varies, often 0% | Designed around travel spend |
| Debit card (non-travel) | Often 1-3% plus ATM fees | Bank-specific, rarely disclosed prominently |
How do you actually check if your card charges this fee?
You have to go looking for it, because no card displays this fee at checkout. U.S. issuers are required to disclose the foreign transaction fee and its terms to consumers in your cardholder agreement, but that disclosure lives inside the general fees section, not on the card itself or on the payment terminal.
Three concrete steps to check before you travel:
- Log into your card issuer's website and search your account terms for "foreign transaction fee" or "international transaction fee." It's a required disclosure, so it exists somewhere in the document.
- Pull up a past statement from a trip abroad, if you have one, and look for a secondary line item under any foreign purchase. If you see one, you're currently paying it.
- Call the number on the back of your card and ask directly. Representatives can confirm the exact percentage faster than digging through PDF terms.
Is the foreign transaction fee the same as a bad exchange rate?
No, and conflating the two is where most travelers lose additional money without realizing it. The foreign transaction fee is a fixed percentage charged on top of a transaction. A poor currency exchange rate is a separate cost, baked into the rate itself before the fee is even applied, and it doesn't show up as a line item at all. This is why a currency exchange rate comparison between your card issuer, a service like Wise, and a local QR payment option can reveal a bigger gap than the stated fee alone suggests.
International ATM fees compound this further. A cash withdrawal abroad can trigger a fee from your own bank, a separate fee from the ATM operator, and an unfavorable exchange rate all at once, on top of any foreign currency conversion fee already built into your card's terms. None of these appear as a single, clearly labeled charge, which is exactly why comparing total cost, not just the advertised fee, matters more than picking a card that claims to have no fees.
Frequently Asked Questions
Does every credit card charge a foreign transaction fee?
No. Basic cards typically charge around 3 percent, but many travel and premium cards from issuers like Chase, Capital One, and American Express waive it entirely.
Is the foreign transaction fee legal to charge without upfront notice at checkout?
Yes. Issuers are required to disclose the fee in your cardholder agreement, but there's no requirement to display it at the point of sale.
Does using a debit card avoid the foreign transaction fee?
Not necessarily. Many debit cards charge a similar percentage-based fee, and international ATM fees on debit withdrawals can add further cost on top.
Are international money transfer fees the same as foreign transaction fees?
No. International money transfer fees apply when you send money across borders through a service or bank wire, while foreign transaction fees apply to card purchases made in a foreign currency.
How do I know if a specific purchase already includes a bad exchange rate?
Compare the rate your issuer used against the rate at the time of purchase from a neutral source. A gap of more than a percent or two beyond the standard fee usually indicates a currency exchange rate markup, not just the disclosed fee.
Can a QR code payment app help avoid these fees?
Apps that let you pay through local QR payment networks convert currency at the point of payment using a disclosed rate, which lets you see the total cost before confirming, rather than discovering a combined markup and fee after the fact on your statement.
About Moreta
Moreta is a FinCEN-registered Money Services Business that gives international travelers a digital wallet built around each country's own QR payment network, from Pix in Brazil to DuitNow QR in Malaysia. Instead of routing a purchase through a card network and an issuing bank, each carrying its own fee structure, Moreta lets you top up from your home bank or card, scan the same QR code a local would use, and see the merchant name, amount, and exact exchange rate before confirming. The platform includes a rate comparison tool so travelers can check total cost, fees and exchange rate combined, against alternatives like a card swipe, an ATM withdrawal, or services like Wise or Revolut, before spending. Funds are held with identity verification, fraud monitoring, and account alerts built in, reflecting the security-first approach the founding team has emphasized publicly.
If you're tired of decoding statement line items after the fact, it's worth comparing what you'd actually pay to spend locally instead. Learn more at Moreta.