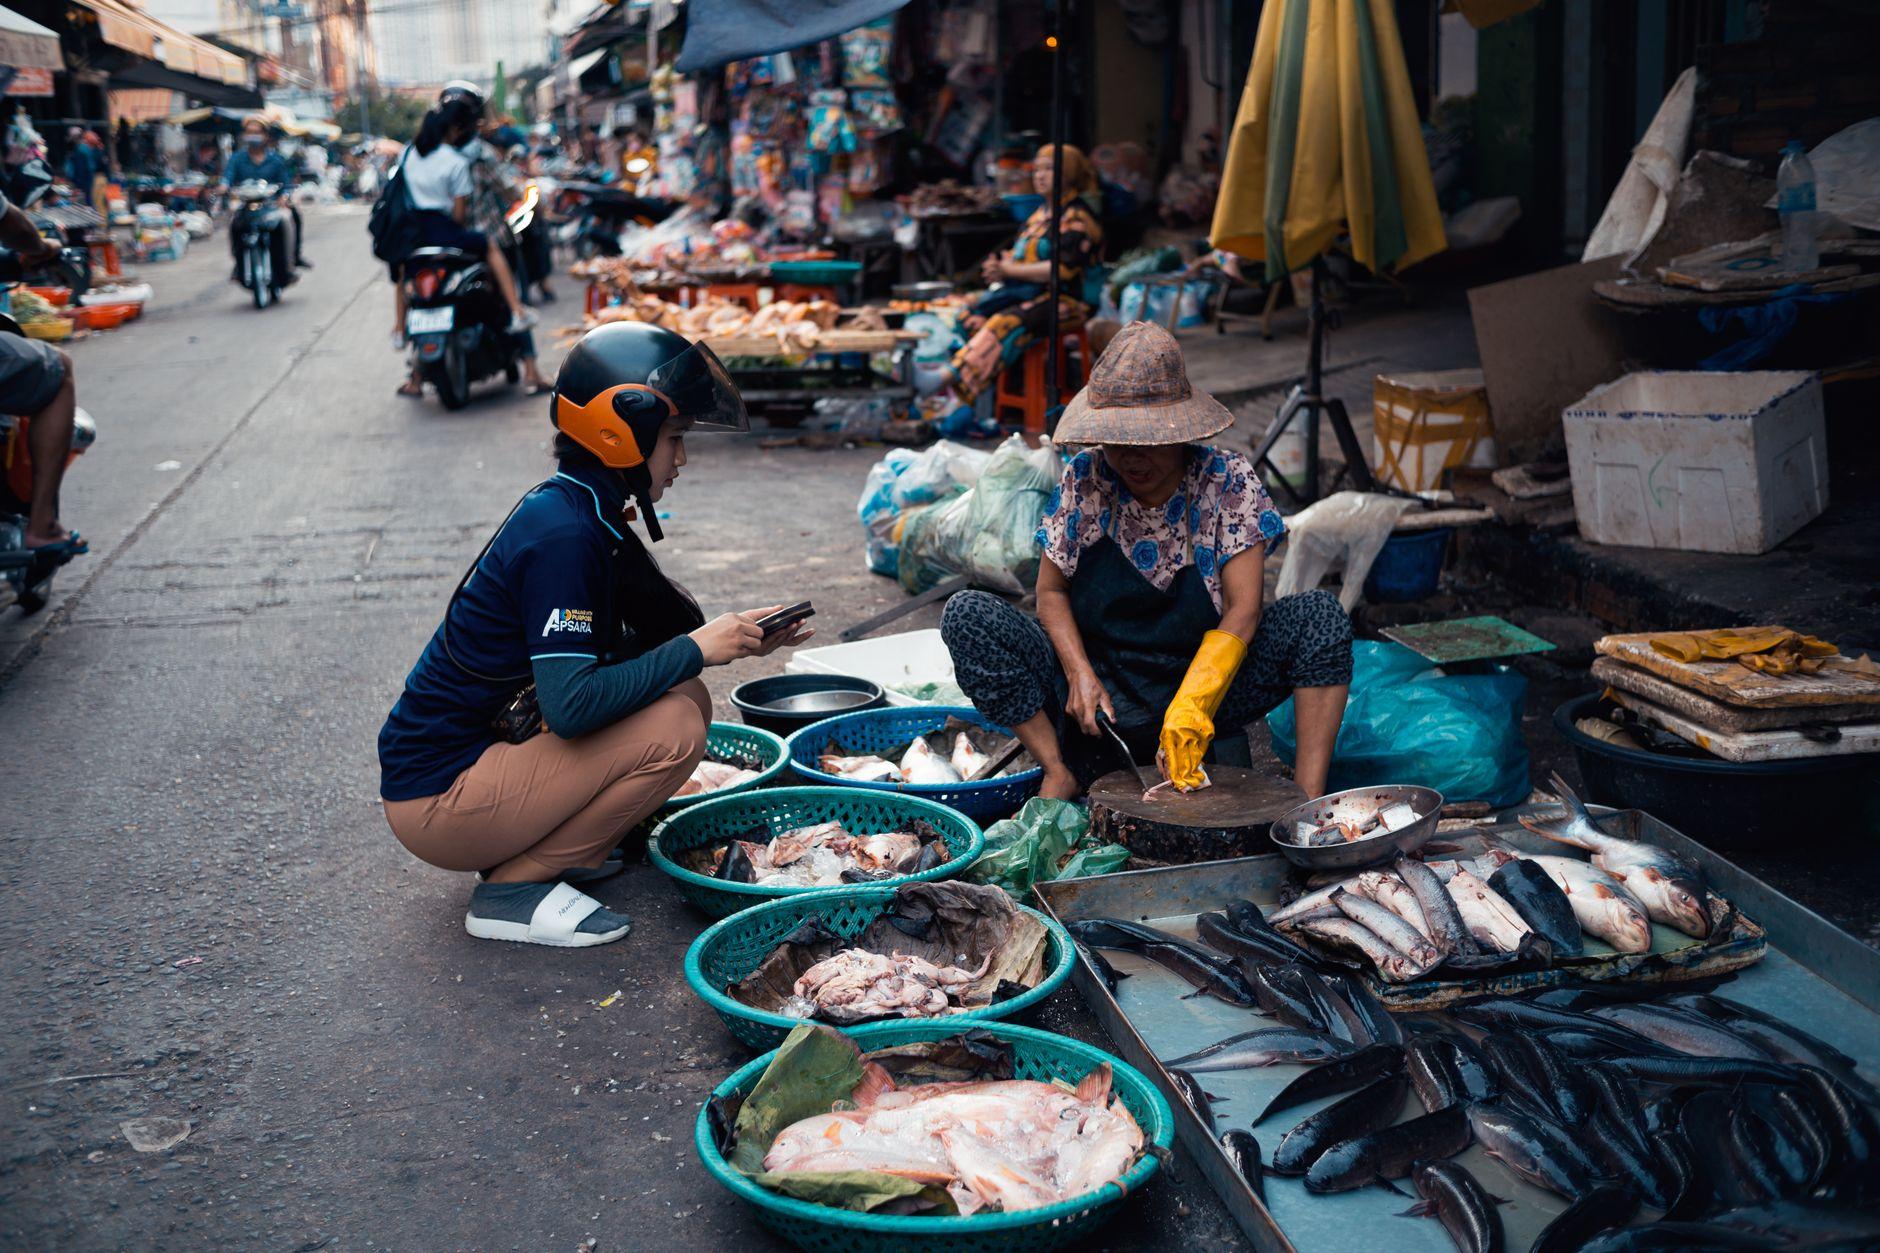
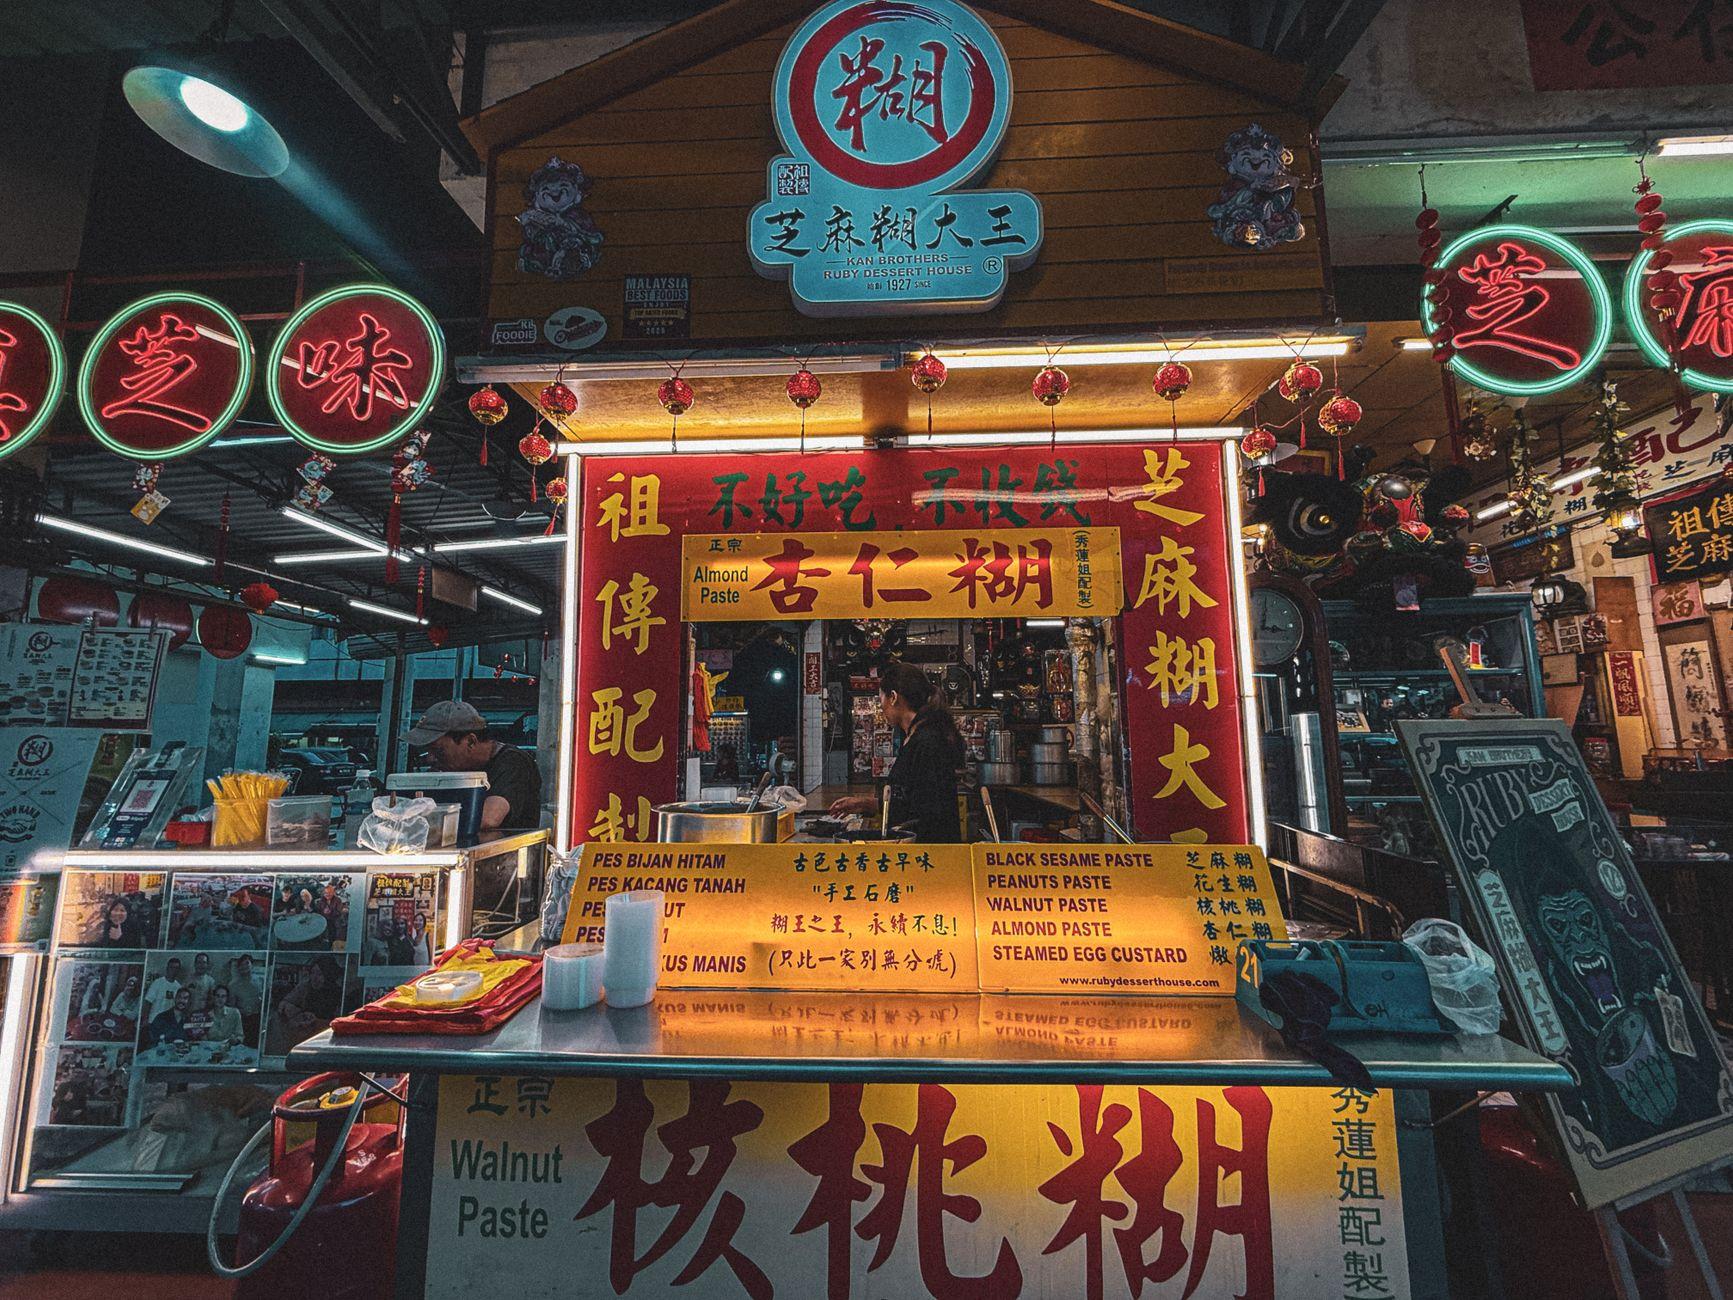
A vendor at Phnom Penh's Central Market watches your phone screen freeze mid-transaction. The KHQR code scanned fine. The payment did not go through. You are not out of money. You have hit a daily cap, and the way you get past it depends on which country you are standing in and which app you are paying from. Cambodia ties a wallet's daily ceiling to how thoroughly its owner has been identity-checked. Malaysia leaves the ceiling to each bank and lets the account holder adjust it in the banking app, with a waiting period before a higher limit takes effect. Confusing the two is the fastest way to stand at a mamak stall in Kuala Lumpur or a psar in Phnom Penh, phone in hand, wondering why a payment that worked yesterday will not clear today.
About the author: Moreta Global Inc. operates a digital wallet built specifically to scan and settle on native QR rails across Asia and Latin America, including KHQR in Cambodia and DuitNow QR in Malaysia, which means tracking how each country's caps actually behave is part of the product's daily operating reality, not an afterthought.
What are the daily QR payment limits in Cambodia and Malaysia?
The two systems cap you differently because they solve different problems. In Cambodia, the National Bank of Cambodia sets wallet limits by verification tier. Under its 2021 circular on know-your-customer procedures, a basic account opened with little more than a phone number can move up to 500 USD or 2,000,000 KHR a day, a partially verified account up to 3,000 USD or 12,000,000 KHR, and a fully verified account up to 10,000 USD or 40,000,000 KHR [dfdl.com]. The Bakong Tourists app follows the same logic: an unverified user sits at the basic tier, and verifying your identity in the app raises the daily limit to 3,000 USD or 12,000,000 KHR, according to the National Bank of Cambodia's user manual [lolc.com.kh]. Cambodian banks also set their own limits for domestic QR use outside the tourist app, and those vary by institution.
Malaysia's DuitNow QR works on a different logic. There is no national tier table. Each bank sets a daily transfer limit that covers DuitNow QR, DuitNow Transfer and interbank GIRO together, up to a ceiling of RM 50,000 a day at the big banks, and the account holder can set it lower or raise it back inside the banking app [cimb.com.my][pbebank.com]. The catch is timing: at Maybank, CIMB and Public Bank an increase only takes effect after a 12-hour cooling-off period, a fraud control so that a stolen phone cannot be used to lift the limit and drain the account in one go. There is no separate tourist tier and no verification step that unlocks more room, because the limit belongs to a Malaysian bank account.
The practical difference: in Cambodia, hitting your cap usually means completing identity verification to move to a higher tier. In Malaysia, hitting your cap usually means you lowered a setting, or your account's limit is lower than your shopping day, and the fix needs half a day's notice.
Why does a verification tier behave differently from an adjustable bank limit?
Malaysia's limit is a dial. Whatever ceiling you have set, up to your bank's RM 50,000 maximum, is available each day, and if you want more you turn the dial in the app and wait out the cooling-off period. It is predictable, and it is entirely in the account holder's hands.
Cambodia's limit is a door with three locks. The amount a wallet can move in a day is a function of what the provider knows about its owner, so a tourist who installed Bakong Tourists at the airport with an email address and no document check is at the 500 USD tier, and no amount of waiting changes that. The lever is verification: upload a passport, pass the check, and the daily ceiling moves to 3,000 USD. A Cambodian resident using a local bank's app faces that bank's own numbers, which can be different again.
Malaysia's system asks "how much do you want available today". Cambodia's asks "who are you", and answers with a ceiling tied to that answer.
Which regulatory bodies actually set these rules?
The National Bank of Cambodia (NBC) regulates and enforces limits for the Bakong system, the infrastructure behind KHQR. Bank Negara Malaysia (BNM), working alongside the national payments network operator PayNet, oversees the rules governing DuitNow QR. Neither central bank publishes an identical rulebook, because Bakong and DuitNow QR are not the same underlying payment rail: Bakong is built around a mobile money and bank account interoperability layer, while DuitNow QR standardizes a single QR format across Malaysian banks and e-wallets for cashless payments Malaysia has adopted widely at retail counters [digitalinasia.com].
A traveler assuming that "QR payments in Southeast Asia all work the same way" is assuming a false equivalence. The National Bank of Cambodia's tiered verification model and Bank Negara Malaysia's bank-set, user-adjustable model reflect two different regulatory philosophies applied to two different technical systems. Cross-border interoperability projects between the two do not merge them: since April 2025, customers of participating Malaysian banks such as Maybank and CIMB can scan KHQR codes in Cambodia from their own apps [bis.org][bnm.gov.my], but their payments still run under their Malaysian bank's limits, and a Cambodian scanning DuitNow QR in Malaysia is still bound by the Bakong tier. The rails can talk to each other. The caps still follow separate rules.
What limits apply if you pay with Moreta Pay instead?
If you are scanning KHQR or DuitNow QR from Moreta Pay, neither of the structures above is your cap, because you are not paying from a Cambodian wallet or a Malaysian bank account. Moreta applies its own limits per country and shows them in the app before you pay. In Malaysia, a single payment can be up to 12,000 MYR and a week's payments up to 24,000 MYR. In Cambodia, the limits are listed in the app's country guide. The full table is on the fees and limits page. The identity check happens once, at signup, with a passport scan and a selfie, so there is no mid-trip verification tier to climb.
How do I avoid hitting a cap mid-transaction?
Plan around the mechanism, not the symptom.
- In Cambodia: If you expect to spend more than 500 USD in a day from a Cambodian wallet, complete identity verification before you need the higher ceiling, not after a payment fails at the register.
- In Malaysia: Check your bank or e-wallet's current daily transfer limit before a big shopping day (Mid Valley Megamall, Jalan Alor food stalls) and raise it at least 12 hours ahead, since the increase does not take effect immediately.
- In both countries: Keep a secondary funding method available. A vendor digging through a drawer for change while you troubleshoot a declined QR scan is not a moment to discover your cap for the first time.
- Carry a modest cash reserve regardless. Rural stalls, parking attendants, and small temple donation boxes in both countries still run on physical currency, and no QR limit adjustment fixes that.
Moreta Pay lets you top up from your home bank or card, scan the same local KHQR or DuitNow QR code the merchant already uses, and see the merchant name, amount, and exact FX rate before confirming. Its limits are its own, shown before you pay, and they do not change with a verification tier. What it cannot do is lift a cap on a Cambodian wallet or a Malaysian bank account you are paying from instead; those belong to the rail and the institution, not to the app scanning the code.
Frequently Asked Questions
Can I raise my Bakong Tourists daily limit like I can with a Malaysian banking app?
Not through a self-service setting. The path to a higher ceiling in Bakong Tourists is completing identity verification in the app, which moves you from the 500 USD basic tier to the 3,000 USD verified tier.
Is RM 50,000 the default DuitNow limit at every Malaysian bank?
No. RM 50,000 a day is the ceiling at the major banks, and some accounts start there while others, such as youth accounts, start far lower. Check the figure in your own banking app, and remember that an increase takes effect only after a cooling-off period of around 12 hours.
Do Cambodian domestic bank QR limits match the Bakong Tourists app limits?
Not necessarily. Individual Cambodian banks set their own transaction and daily caps for domestic QR use, separate from the Bakong Tourists app's tiered structure.
If I'm a tourist in Malaysia, do I need a Malaysian bank account to adjust a DuitNow QR limit?
The limit belongs to the bank or e-wallet account the payment comes from, so only the account holder can change it. A visitor paying through a foreign-funded wallet such as Moreta Pay is bound by that wallet's own limits instead.
Does the Cambodia-Malaysia cross-border QR link change either country's caps?
No. The linkage lets customers of participating Malaysian banks scan KHQR in Cambodia, and Bakong users scan DuitNow QR in Malaysia [bis.org][bnm.gov.my], but each payment still runs under the limits of the account it comes from.
Why do cashless payments in Malaysia rely on a QR standard rather than cards?
DuitNow QR gives merchants a single, bank-agnostic code that works with any participating bank or e-wallet app, which is a major reason cashless payments malaysia adoption has scaled at hawker stalls and small retailers without requiring separate card terminals.
About Moreta
Moreta Global Inc. is a Delaware corporation and FinCEN-registered Money Services Business, backed by Y Combinator. The company built its wallet specifically to interface with native QR standards like KHQR and DuitNow QR rather than routing payments through a generic international card network, which means tracking country-specific rules like transaction caps is core product research, not marketing copy. If you are planning travel across either rail and want to see exchange rates, fees and limits before you land, visit Moreta.
References
- Launch of the Cambodia-Malaysia cross-border QR phase 2 | Bank for International Settlements (bis.org)
- Launch of Cambodia-Malaysia Cross-Border QR Payment Phase 2 | Bank Negara Malaysia (bnm.gov.my)
- AR2025: Promoting Safe & Efficient Payment & Remittance Services - Bank Negara Malaysia (bnm.gov.my)
- Cambodia: New Transaction Amounts for KYC Procedures for Financial Institutions and Payment Service Providers | DFDL (dfdl.com)
- Bakong Tourists user manual | National Bank of Cambodia, via LOLC (lolc.com.kh)
- What is the allowed limit? | CIMB Clicks FAQ (cimb.com.my)
- Daily transaction limit | Public Bank (pbebank.com)
- How Do Digital Payments Work in Southeast Asia in 2026? QR, Wallets, and Cross-Border Rails (digitalinasia.com)