A vendor at Chatuchak market in Bangkok holds up her phone, waiting. You tap your travel card, and somewhere between the terminal and your bank, your dollars just became baht at whatever rate the app decided to give you that second. You didn't choose that rate. You didn't get a preview. It just happened, the way it happens at every counter, every day, on every trip.
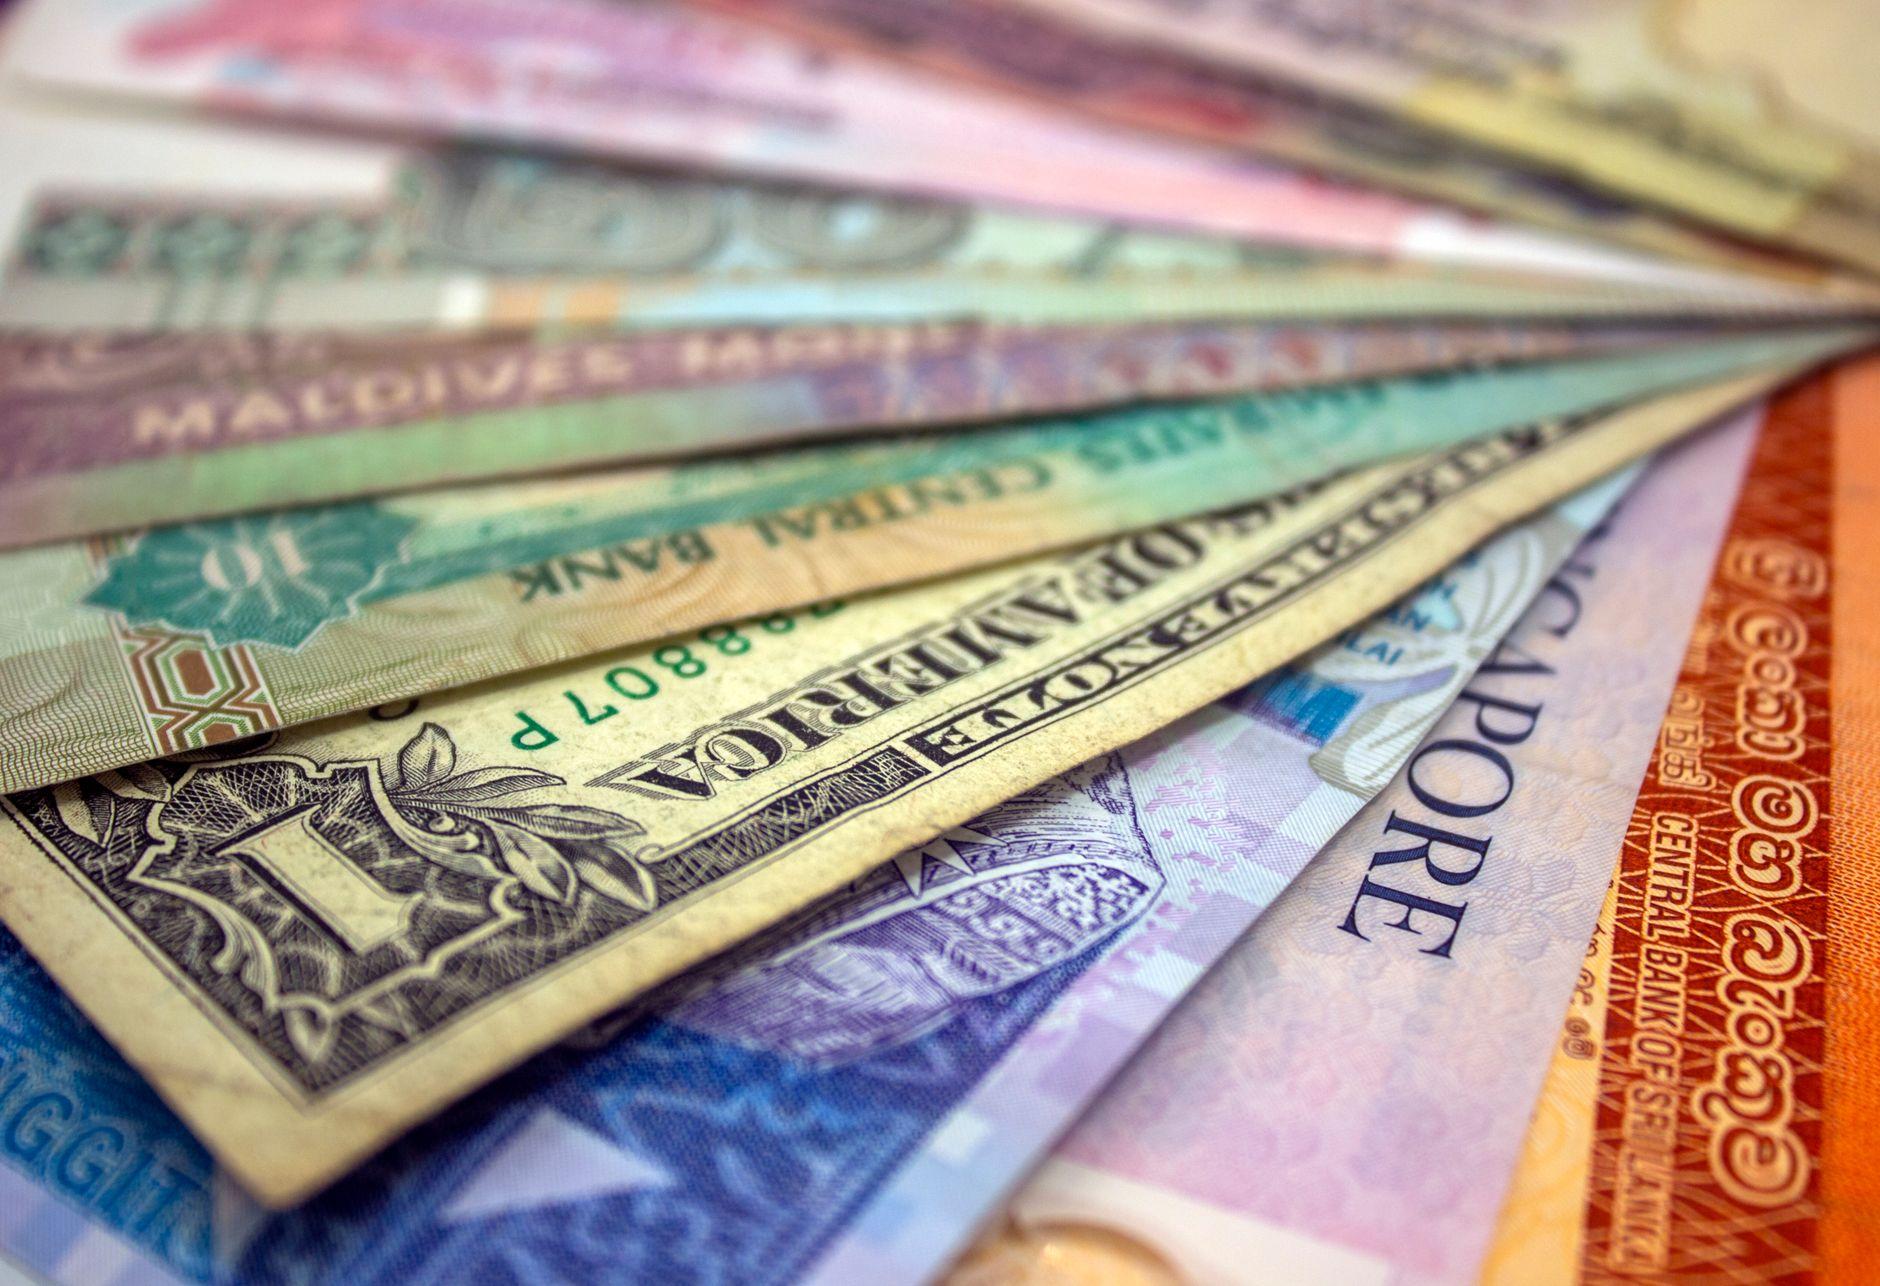
That single moment, the point where your home currency turns into someone else's, is the entire multi-currency wallet question. Some apps force that conversion the instant you tap or scan. Others let you hold a balance in idle currency and convert only when you decide to. The difference sounds technical. It is actually the single biggest factor in how much of your money survives a trip abroad. A multi-currency wallet works by pairing your funds with local receiving accounts or rails in different currencies, so a payment can settle locally without your money ever needing to touch a central, single-currency ledger [airwallex.com]. Whether that conversion happens automatically at the point of sale, or only when you choose, determines both your fees and your exposure to rate swings.
About the Author: This piece is written by the Moreta team, a FinCEN-registered Money Services Business built specifically around cross-border QR payments in Asia and Latin America, where local rails like KHQR, DuitNow, and Pix settle exclusively in local currency and conversion timing has a direct, measurable effect on what travelers spend.
What Is a Multi-Currency Wallet, Exactly?
You hold funds in multiple currencies inside a single account without needing a separate bank account for each one. Under the hood, it works by linking your funds to local receiving accounts or settlement rails in different countries, so a payment in Malaysian ringgit or Peruvian soles can clear locally instead of routing through a single home-currency ledger [airwallex.com][suissebank.com]. Some wallets stop there, showing you separate currency balances you manage yourself. Others sit on top of that structure and convert automatically the moment you spend, so you never see a currency balance at all, only a running total in your home currency.
The difference between conversion timing that you control versus conversion timing that the app controls is not the technology, it's what actually happens to your money. Does the conversion happen when you decide, or when the terminal decides?
Why Do Some Wallets Force Conversion at the Point of Sale?
Forced conversion happens because the wallet is architected around a single home-currency balance, with foreign spending converted in real time at checkout. This is how most international travel debit card products and travel money cards work by default: you load or hold one currency, and every foreign transaction triggers an automatic FX conversion at whatever rate the platform applies at that instant.
The appeal is obvious. You never have to think about currency. You tap, it converts, done. But that convenience has a cost, and it isn't always visible on the receipt. Fintechs like Wise and Revolut typically apply mid-market exchange rates for real-time conversions, but Revolut adds a weekend markup, often around 1 percent, when foreign exchange markets are closed for its Standard plan (a smaller markup applies on the Plus plan), while its Premium, Metal, and Ultra tiers are not subject to this weekend surcharge. Wise, meanwhile, charges a consistent, itemized fee regardless of what day it is. If your trip happens to fall on a Saturday and you're on a lower-tier plan, forced conversion at the point of sale can quietly cost you more than the same purchase made on a Tuesday.
This is also where dynamic currency conversion (DCC) becomes a separate villain worth naming. At ATMs and card terminals abroad, you're sometimes offered the choice to be charged in your home currency instead of the local one. Always decline it. DCC almost always applies a worse rate than letting your card network or wallet handle the conversion, and it's a different mechanism entirely from the wallet-level forced conversion discussed above, layered on top of it if you're not paying attention.
Why Do Some Wallets Let You Hold Balances Idle Instead?
An idle-balance wallet lets you hold a target currency without immediately converting it, so you decide when the exchange happens rather than having it triggered automatically by a purchase. Holding idle balances in multiple currencies allows a user to convert funds manually during weekday market hours, avoiding both weekend markups and the specific FX markup applied at the moment of a real-time, point-of-sale conversion.
Think of it the way a small importer manages inventory. A shop that pre-orders stock in bulk during a supplier's sale gets a better unit price than one that orders piece by piece whenever a customer walks in. Holding an idle currency balance is the same logic applied to money: you convert in a batch, on your schedule, instead of paying the retail-moment rate every single time you spend.
The tradeoff is that idle balances aren't free either. Multi-currency wallets generally don't charge interchange fees to the consumer, but they can carry account funding fees, inactivity fees, or subscription costs tied to premium tiers that unlock higher conversion limits. An idle balance also means your money is sitting in a currency that could weaken against your home currency before you spend it, which is a real risk if you're holding funds for weeks rather than days.
How Does This Play Out With Local QR Payment Rails?
Local QR payment networks in Asia and Latin America change the calculation because they typically settle exclusively in local currency, no matter what currency your wallet holds. DuitNow in Malaysia, Pix in Brazil, KHQR in Cambodia, and QR Ph in the Philippines are all built on standardized QR formats, largely aligned with the EMV QR Code Specification for Payment Systems, and designed for real-time local currency settlement rather than cross-border card rails. That means the conversion has to happen somewhere between your foreign balance and the merchant's local account. The only question is whether it happens transparently, before you confirm, or invisibly, after you've already tapped.
This is the specific gap Moreta Pay is built around. You top up from your home bank or card in your own currency, scan the same local QR code the vendor already uses, and see the merchant name, the amount, and the exact FX rate before you confirm anything. No mystery markup, no guessing what a weekend surcharge did to your total. It's a QR code payment app in the sense that it plugs directly into rails locals already use, but the conversion step is shown to you upfront rather than buried in a settlement you can't see.
How Does This Compare to Other Travel Payment Options?
| Approach | Conversion timing | Where it shows up |
|---|---|---|
| Wise | Real-time, mid-market rate, itemized fee | Multi-currency account, no weekend surcharge |
| Revolut | Real-time, with weekend FX markup on lower-tier plans | Multi-currency card, rate varies by day and plan |
| Cash from ATM | Immediate, plus possible DCC prompt | Physical withdrawal, local currency |
| Moreta Pay | Shown before confirmation, at local QR scan | Direct local rail (DuitNow, Pix, KHQR, QR Ph) |
The Wise vs Revolut comparison usually comes down to this exact weekend-timing detail: Wise's fee structure doesn't shift based on the day, while Revolut's does for customers on its Standard and Plus plans, though higher-tier Revolut customers aren't subject to that weekend surcharge. Neither product is architected specifically around local QR rails the way Moreta is, since Wise and Revolut both operate as multi-currency account and card platforms rather than direct QR-scanning wallets. Other players approach the same problem from different angles.
Frequently Asked Questions
Is a multi-currency wallet the same as a travel card?
Not exactly. A travel money card is often a single physical or virtual card tied to a wallet, while the wallet itself is the underlying account structure that can hold or convert multiple currencies [multipass.co].
Do idle currency balances always save money?
Only if you time the conversion during weekday market hours and avoid inactivity or subscription fees. If you convert impulsively or hold a balance for a long period while rates move against you, the savings can disappear.
What's the best exchange rate app for comparing fees before I travel?
Look for one that shows the exact rate, the fee, and the total spending power side by side before you confirm a payment, rather than one that only discloses the rate after the transaction clears.
Does DuitNow in Malaysia require a Malaysian bank account?
DuitNow QR is Malaysia's national QR standard, built for local bank-to-bank and e-wallet transfers. Visitors without a local account or phone number are typically locked out of scanning it directly, which is the specific gap a foreign-currency-funded wallet is designed to close.
Why does Pix in Brazil always settle in Brazilian real?
Pix is Brazil's instant payment system, built for local currency settlement between Brazilian accounts. Any foreign balance used to pay a Pix QR code has to convert to real somewhere in the transaction chain.
Are currency conversion fees the only cost I should watch for?
No. Weekend markups, fair-usage caps once you exceed free monthly conversions, and account fees can all add up separately from the headline FX fee.
Is my idle balance protected if the platform fails?
It depends on the platform. A non-bank fintech is not itself FDIC-insured. Some pass customer funds through to a partner bank, where pass-through insurance can apply if that bank fails: Revolut's US card accounts sit at Lead Bank, for example, and Wise US balances are covered only when you opt into its interest feature. Otherwise protection relies on the platform safeguarding customer funds at licensed partner banks under money-transmitter rules. Check the specific platform's disclosure before holding a large idle balance.
About Moreta
Moreta Global Inc. is a Delaware corporation and FinCEN-registered Money Services Business, backed by Y Combinator. The platform is built specifically for the local QR rails travelers actually encounter on the ground, in markets including Malaysia, Cambodia, Brazil, and China, alongside Vietnam, Thailand, the Philippines, Laos, South Korea, Mongolia, Argentina, Peru, Bolivia, and Colombia. Funds move through familiar rails, a US bank account linked through Plaid, SEPA, UK Faster Payments, Canadian Interac e-Transfer, Australian PayID, cards, Apple Pay, Google Pay, or USDC (money added with crypto can't be spent in Thailand, Cambodia or China), and every conversion is shown before you confirm, not after. Identity verification and 24/7 fraud monitoring run underneath every transaction so the tradeoff between convenience and control doesn't have to come at the expense of security.
If you're planning a trip through any of these markets and want to see the exact rate before you tap, not after, visit Moreta and check what your money is actually worth before you spend it.
References
- What is a Multi-Currency Wallet and How Does it Work? (airwallex.com)
- Multi Currency Wallet: Features to Look for 2025 | Suisse Bank News (suissebank.com)
- What is a multi-currency wallet? How to pick one? | MultiPass (multipass.co)