The machine on Jalan Alor blinks, whirs, and goes silent. Your card is gone. There is no receipt, no error code you understand, just a slot that used to give money and now gives nothing. If an ATM has just eaten your card in Kuala Lumpur, Phnom Penh, or Sao Paulo, the fix is the same everywhere: stay at the machine, call your bank's card-lock line immediately, note the ATM's exact location and bank operator, and file a retrieval request in person at that bank branch during business hours. Most swallowed cards are retrievable, but the process can take anywhere from same-day to several business days depending on the bank and country, and in the meantime you still need a way to pay for dinner, a Grab ride, or your hostel deposit.
What Should I Do the Moment an ATM Eats My Card?
Stay put. The single biggest mistake people make when an ATM eats their card is stepping away to find staff or call from somewhere quieter, and losing track of exactly which machine and which bank's logo was on it.
Before you move:
- Photograph the ATM screen if it still shows an error message.
- Write down the exact street address, the bank name printed on the machine, and the time.
- Check for a second slot or a "card return" tray. Some ATMs briefly re-eject a card after a failed read before locking it inside permanently.
- Do not walk away from the ATM. Note the time, machine ID, and bank name on the terminal before you do anything else.
- Call your card issuer's 24-hour lost/stolen card line first to freeze the card, then contact the ATM's bank separately to start retrieval.
- Retrieval timelines vary by bank and country; some machines auto-return unclaimed cards to the branch, others send them to a regional processing center.
- Carry a backup way to pay that does not depend on plastic, since a frozen or swallowed card leaves you with zero access to your primary account for the rest of the trip.
- A digital wallet funded from your home bank or card, like Moreta, lets you keep paying local merchants by QR code even while your physical card is stuck in a machine or a bank vault.
If nothing comes out after a minute or two, the card is inside the machine, not lost. That distinction matters because "ATM ate my card" almost never means the card is gone for good. It means it is sitting in a locked cassette that only bank staff can open, and the machine has probably already logged the retention internally.
ATM Card Retention Mechanisms
An ATM retains a card when its internal logic flags the transaction as unsafe to complete, not because of a random malfunction. Common triggers include entering the wrong PIN multiple times, a card left in the slot too long after the cash is dispensed, a chip that fails to read cleanly, or the issuing bank flagging the card for a security check mid-transaction [clientebancario.bde.es]. Retention is a deliberate mechanism, similar to a subway turnstile locking after too many failed taps: the system is designed to fail closed rather than let an ambiguous transaction through.
Who Do I Call First, My Bank or the ATM's Bank?
Call your own card issuer first. Your bank can freeze the card remotely within minutes, which matters because a card sitting inside a foreign ATM is still technically active until you report it [bankenverband.de]. Freezing it prevents anyone who might access the machine's internals from using it before retrieval.
Separately, contact the bank that operates the ATM, since they are the ones physically holding your card. German banking guidance is explicit on this two-track approach: report the card as blocked with your own bank without delay, and independently follow up with the ATM operator to arrange retrieval [bankenverband.de]. Spanish consumer banking guidance gives the same instruction, framing speed as the priority once a card is swallowed [clientebancario.bde.es].
How Do I Get My Card Back in Kuala Lumpur?
Malaysian banks that operate ATMs, including Maybank, CIMB, and Public Bank, generally route a swallowed card to the branch nearest the machine, and you retrieve it in person with your passport. Bring the ATM's exact address and the approximate time of the transaction, since branch staff will need to locate the specific retention log. If the ATM belongs to a bank where you do not hold an account, expect the process to run slower, since you are not a verified customer at that branch.
How Do I Get My Card Back in Phnom Penh?
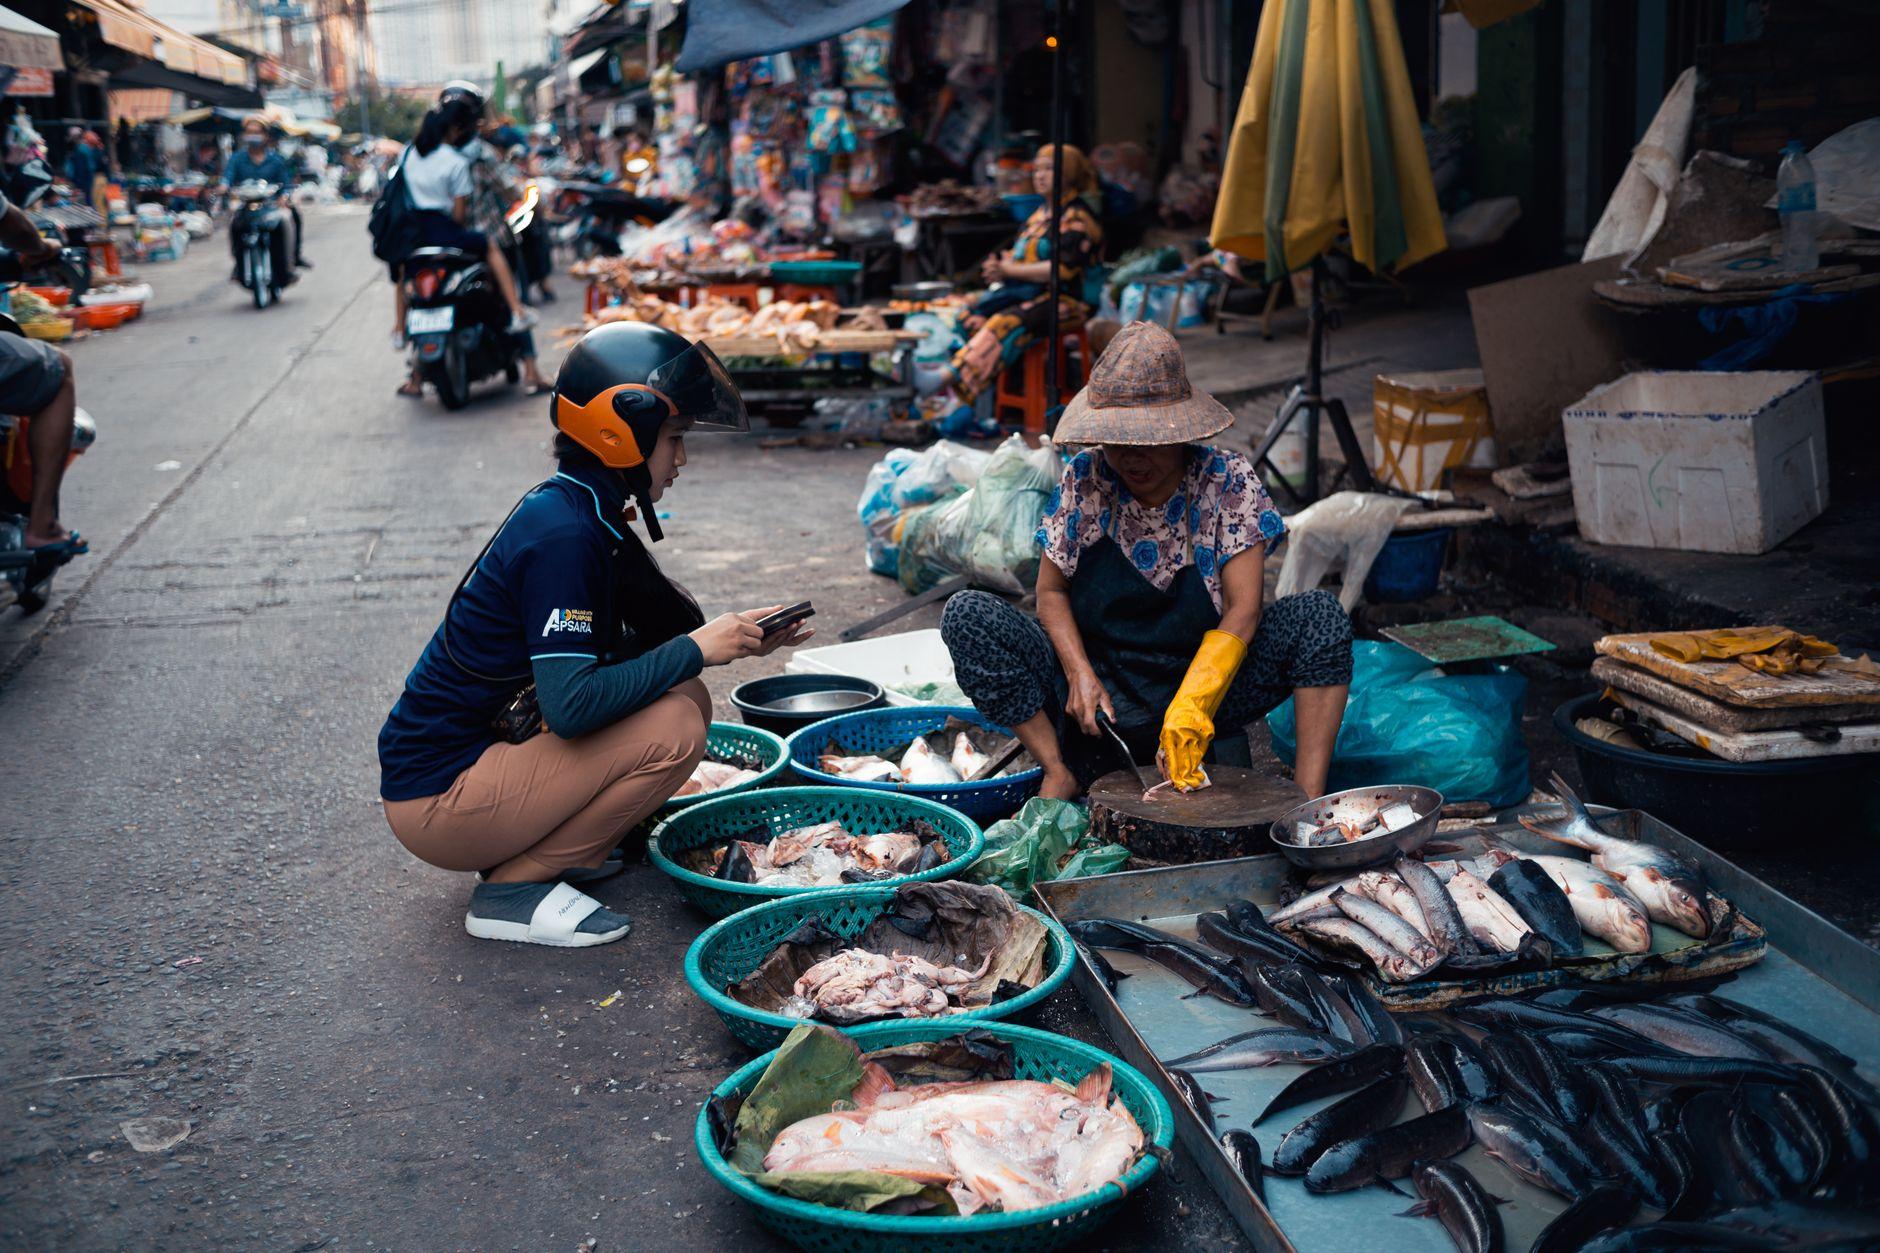
Cambodian ATMs operated by banks like ABA or Acleda follow a similar pattern: the card sits in the machine's internal cassette until a branch employee opens it during a scheduled service window, which may not be daily at smaller branches. If your hotel or guesthouse is nearby, ask staff which branch services that specific ATM, since retention cassettes are not always cleared at the location where the card was swallowed.
How Do I Get My Card Back in Sao Paulo?
Brazilian banks, including Bradesco, Itau, and Banco do Brasil, typically require you to present ID and the card's associated account details at the branch that owns the machine. Sao Paulo's ATM density means there is often a competing bank branch across the street, which is not the one you want, so confirm the logo on the machine matches the branch you are walking into.
What Do I Do for Money While the Card Is Stuck?
A frozen card and a swallowed card both leave you unable to withdraw cash or tap to pay, sometimes for several business days, and rebooking a flight or paying a Grab driver in Kuala Lumpur, or an Uber in São Paulo, does not wait for a bank's retrieval schedule.
Two things help here. First, never travel with only one card or one payment method, since a single point of failure at a machine is exactly the scenario described above. A shortlist of the best travel card 2026 options usually includes at least one no-foreign-transaction-fee card as a backup, kept in a separate bag from your primary card.
Second, a wallet-based international money transfer app that does not depend on a physical card at all gives you a way to keep paying local merchants directly. Moreta works by connecting to your home bank account or card ahead of time, so the funding step happens before you ever touch a foreign ATM. Once loaded, you scan the same QR code the merchant already uses, whether that is a DuitNow QR payment at a Kuala Lumpur mamak stall, a KHQR code at a Phnom Penh market stall, or a Pix payment in Brazil at a Sao Paulo padaria, and the app shows you the merchant name, the amount, and the exact exchange rate before you confirm. DuitNow QR has more than 3 million merchant touchpoints in Malaysia, about 4.5 million merchants accept KHQR in Cambodia, and Pix is accepted by the vast majority of businesses in Brazil, which means QR code payment in Malaysia, Cambodia, or Brazil covers far more everyday spending than a card swipe would in the same markets.
Frequently Asked Questions
Will I get my card back after an ATM eats it?
In most cases, yes. The card is retained inside the machine's cassette, not destroyed, and retrieval through the operating bank's branch is standard procedure [seabank.com.vn].
How long does ATM card retrieval take?
The bank and how often that branch clears its retention cassette varies; some do it daily, others on a set schedule. Ask the branch directly rather than assuming a timeline.
Should I just cancel the card instead of waiting for retrieval?
If you have already frozen it and have a backup payment method, cancelling and requesting a replacement sent home is often simpler than waiting on a foreign retrieval process.
Can dynamic currency conversion cause a card to get flagged and swallowed?
Not directly, but always decline dynamic currency conversion at ATMs and terminals regardless. Choose to be charged in local currency, since DCC applies a worse exchange rate on top of whatever fees your card issuer charges.
Does Moreta replace the need for a physical card entirely?
No. Keep a card and a modest cash reserve for situations Moreta does not cover, like rural toll booths or informal vendors, but a QR-based wallet removes the ATM as a single point of failure for daily spending.
Is QR payment widely accepted by small vendors, not just big stores?
Yes, in all three markets. DuitNow, KHQR, and Pix were built as national standards specifically so small stalls and independent vendors could accept digital payment without a card terminal.
About Moreta
Moreta Global Inc. is a Delaware corporation, FinCEN-registered Money Services Business, and Y Combinator-backed company (Summer 2024 batch) that built its wallet around the reality that travelers need a payment method independent of foreign ATMs and card networks. The app funds from a US bank via ACH, a card, or other supported rails, then lets you pay directly through local QR standards like DuitNow in Malaysia, KHQR in Cambodia, and Pix in Brazil, with the exchange rate shown before you confirm each payment. It is not a replacement for a bank account, but it is built to be the thing in your pocket that still works when a card is not.
If you are planning a trip through Kuala Lumpur, Phnom Penh, Sao Paulo, or elsewhere Moreta operates, set up your wallet before you fly. Visit Moreta to see which local rails are supported at your destination.
References
- What to do if the atm swallows your card - Cliente Bancario, Banco de España (clientebancario.bde.es)
- What should you do if the ATM 'swallows' your card?... | Association of German Banks | Association of German Banks (bankenverband.de)
- 3+ Steps to do when your ATM card is swallowed to get it back FAST (seabank.com.vn)