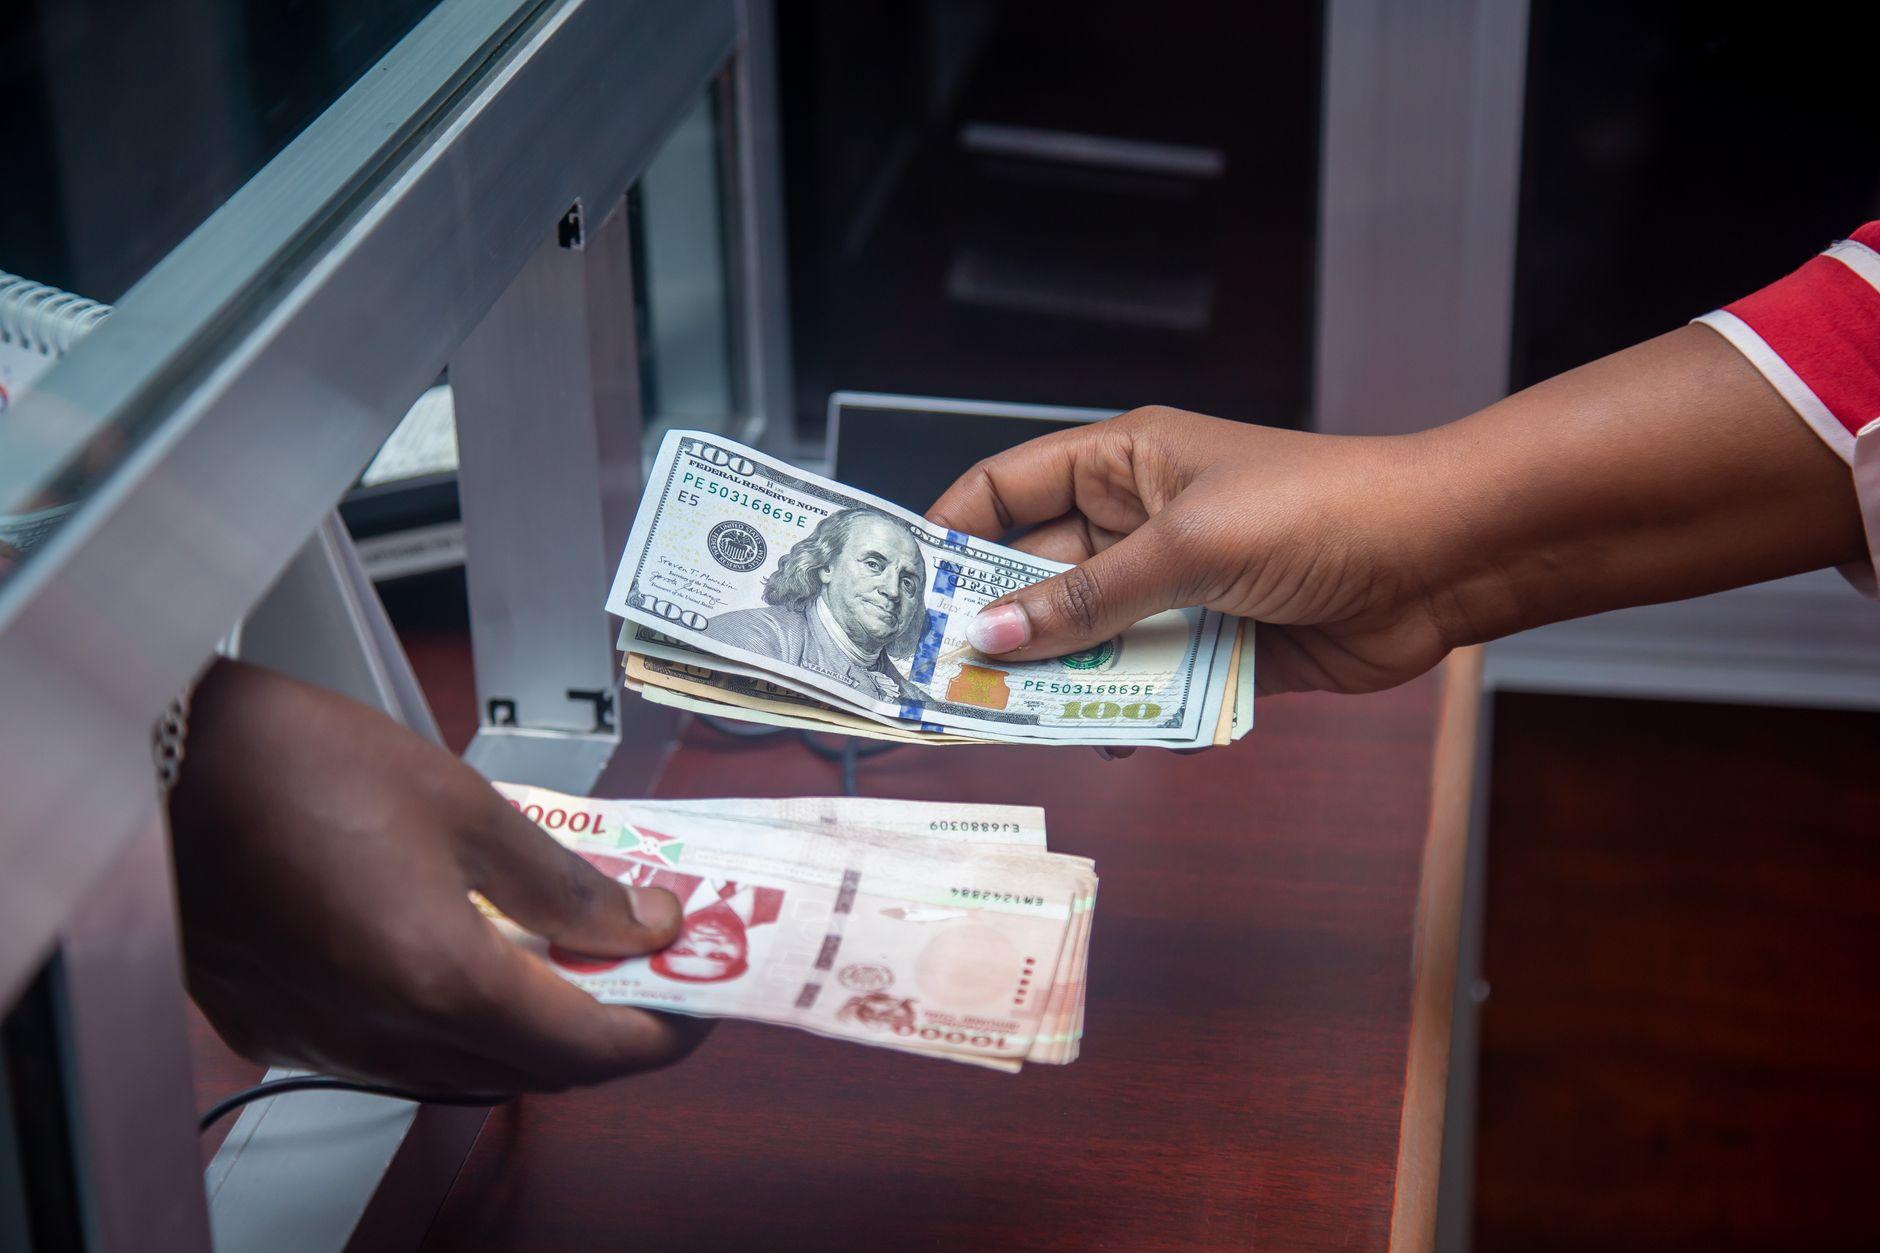
You're at your bank's counter on a Tuesday afternoon, envelope in hand, waiting to pick up a sealed stack of pesos or baht you ordered three weeks ago. The teller slides it across. You don't open it to count-you trust the math was done right. But the math was done the day you placed the order, at a rate that's already moved twice in the markets, and you just paid roughly 3% to 6% above what the currency was actually worth that day on a major currency, up to about 10% on a less common one, plus a flat fee on top. For most travelers, a card, a QR-based wallet, or even the ATM at your destination airport will get you more spending power from the same starting amount. The only scenario where pre-ordering cash makes sense is a remote destination with no reliable card acceptance and no functioning ATM network, and even then, ordering the smallest amount that gets you through the first 24 hours is the smarter move.
What does it actually cost to pre-order foreign cash from a bank?
Pre-ordering foreign currency from a bank means paying two separate costs stacked on top of each other. The first is the exchange rate markup itself: banks buy currency at close to the interbank rate and sell it to you at a retail rate that typically runs 3% to 6% higher, with some banks pushing the spread as high as 10% depending on the currency and order size. The second cost is a flat delivery or handling fee, which hits hardest on small orders. Order $200 worth of Vietnamese dong two weeks before a trip and a flat $7.50 delivery fee, which is what Bank of America charges on orders under $1,000, is a much bigger percentage hit than the same fee on a $2,000 order.
Search "foreign currency exchange bank" and most results funnel you toward branch pickup or home delivery of cash, both of which are priced this way [bankofamerica.com][chase.com]. The bank doesn't put the total cost front and center the way a percentage-based app does.
Why is locking in a rate weeks before your trip a bad idea?
Locking in a pre-order rate weeks in advance means you are betting that today's rate is as good as it gets. Currency markets move daily, sometimes by more than a bank's markup itself, so ordering cash a month out exposes you to a rate that could be stale by the time you land. Financial planning guidance on travel money exchange comparison generally points the same direction: exchange closer to the date you need the money, and use tools that show you the live rate rather than a rate quoted once and held [uk.changegroup.com].
A bank pre-order is a single transaction executed once, at whatever rate is quoted that day, with no ability to adjust. A wallet that converts at the point of payment, by contrast, prices every transaction independently against the live rate at that moment. You are never locked into a rate you agreed to weeks earlier for a country you haven't landed in yet.
Is an ATM withdrawal abroad cheaper than a bank pre-order?
An ATM withdrawal abroad typically costs less than a pre-ordered stack of cash, even though ATM fees have their own structure worth understanding. Foreign ATMs in popular travel destinations across Asia and Latin America typically charge a flat fee of $3 to $7 per withdrawal, plus a foreign exchange markup or dynamic currency conversion fee of 1% to 3% on the withdrawal amount. On a $200 withdrawal, that's roughly $5 flat plus up to $6 in markup, versus a bank pre-order that could apply a 3% to 10% markup on the entire amount before any delivery fee.
The gap widens further if you decline dynamic currency conversion at the terminal. DCC is the option a foreign ATM or card terminal gives you to be charged in your home currency instead of the local one. The DCC provider sets its own conversion rate, layered on top of whatever your card network charges. Always choose to be charged in the local currency, never your home currency, and decline DCC every time it's offered.
How do currency exchange apps compare to bank pre-orders?
Currency exchange apps that price transactions off the mid-market rate with a transparent, disclosed fee are structurally different from how a bank prices a cash order. Wise charges a percentage-based fee starting around 0.23% on top of the mid-market rate with no spread. Revolut offers the interbank rate with no spread during weekday market hours, though weekend transactions and amounts over plan limits carry markups. OFX charges no transfer fee but builds its margin, typically about 0.5% to 1.5% and sometimes more on minor currencies, into the exchange rate itself.
| Method | Typical markup over interbank rate | Additional fees | Rate known before you spend? |
|---|---|---|---|
| Bank cash pre-order | 3% to 10% | Flat delivery/handling fee | Locked in weeks ahead |
| Foreign ATM withdrawal | 1% to 3% (if DCC declined) | $3 to $7 flat per withdrawal | Set at withdrawal moment |
| Wise | ~0% spread | ~0.23%+ fee | Shown before sending |
| Revolut | ~0% weekday | Weekend/plan-limit fees | Shown before sending |
| QR wallet (Moreta) | Shown at point of sale | Disclosed per transaction | Shown before you confirm |
Moreta's wallet applies the same principle a QR-based payment needs to work at all: you top up from a home bank account or card, scan the merchant's actual local QR code, whether that's DuitNow in Kuala Lumpur, KHQR in Phnom Penh, or Pix in São Paulo, and see the merchant name, the amount, and the exact FX rate before you confirm anything. Seeing the rate before committing is something a pre-ordered stack of cash cannot offer, because the rate was already fixed the day you ordered it.
What role do foreign transaction fees play beyond the exchange rate itself?
Foreign transaction fees are a separate charge, typically applied by your card issuer on top of any exchange rate markup, and they compound the cost of using a card that wasn't designed for international spending. A card with no foreign transaction fee removes one layer of cost, but it doesn't fix the underlying exchange rate the transaction clears at, which is a different problem than the one a low-fee card solves.
Airport and street-corner exchange bureaus carry worse foreign cash exchange rates than either a bank pre-order or an app, precisely because of their high overhead and low competition in transit hubs.
When does pre-ordering cash actually make sense?
Pre-ordering foreign cash makes sense in a narrow set of cases: a first destination with limited card acceptance, a rural arrival point with no functioning ATM, or a country where temple donations, rural markets, small-village vendors, and parking attendants still expect cash. Keep a modest, specific reserve, something like $40 to $60 equivalent in small bills, rather than assuming a QR code or card will cover every transaction.
Frequently asked questions
Is it cheaper to exchange currency at the airport or order it in advance from my bank?
Airport bureaus tend to have the worst rates of any channel; bank pre-orders avoid the airport markup but still carry a spread of roughly 3% to 10% plus delivery fees.
What's the safest way to carry money abroad in 2026?
A small cash reserve for rural areas and cash-only vendors, plus a card or wallet with transparent, disclosed rates for everything else.
Do banks disclose their exchange rate markup before I order cash?
Regulation E's Remittance Rule requires disclosure of rate, fees, and final amount for many electronic transfers, but a branch cash pickup isn't always treated identically, so ask for the total cost breakdown before paying.
Should I always decline dynamic currency conversion?
Yes. Choosing to be charged in local currency, not your home currency, avoids the extra markup DCC providers add on top of standard card network fees.
Are ATM withdrawal fees abroad worth it compared to pre-ordered cash?
A $3 to $7 flat fee plus a 1% to 3% markup on the withdrawal amount beats a bank's 3% to 10% markup on pre-ordered cash.
Can a QR-based wallet replace foreign cash entirely?
In cities and established merchant networks across Asia and Latin America, largely yes. In rural areas, temples, or informal markets, cash is still necessary.
About Moreta
Moreta Global Inc. is a Delaware corporation, FinCEN-registered Money Services Business, and Y Combinator-backed (Summer 2024 batch). The company built its wallet around the idea that travelers should see the exact rate and fee before a payment clears, not after, and that paying through a country's native QR network, VietQR, Thai QR and PromptPay, KHQR, QR Ph, OnePay, DuitNow QR, SeoulPay, QPay, WeChat Pay, Pix, Argentina's interoperable QR through Mercado Pago and MODO, Yape and Plin, Bolivia's QR Simple, or DaviPlata, Bre-B and Nequi, beats carrying cash or relying on card networks not built for local rails. Funding works through a US bank account linked through Plaid, SEPA, UK Faster Payments, Canadian Interac e-Transfer, Australian PayID, cards, Apple Pay, Google Pay, or USDC, giving travelers a way to convert at the moment of payment rather than weeks in advance. Identity verification happens at signup and transactions are monitored around the clock, with funds held through licensed banking partners.
If you're weighing a bank cash pre-order against better options for an upcoming trip, compare the real numbers before you commit. Visit Moreta to see how the rate and fees look side by side.
References
- Exchange and Order Foreign Currency from Bank of America (bankofamerica.com)